
5 Signs Your Mutual Fund Portfolio May Need a Review
A mutual fund portfolio usually does not become complicated overnight.
One SIP begins for retirement. Another starts after a salary increase. A lump sum is invested after a bonus. A tax-saving fund remains in the portfolio. Later, another scheme is added because its recent returns look attractive.
Individually, each decision may have made sense at that time. But after several years, you may know the names and current values of your funds without being completely sure why every one of them is still there.
That is when a mutual fund portfolio review becomes useful. A review does not automatically mean selling funds, stopping SIPs or searching for replacements. Its first job is much simpler: Check whether the portfolio still fits the life, goals and financial requirements it was meant to support.
India had more than 28.35 crore mutual fund folios by August 2026, so accumulating investments over time is hardly unusual. But having more investments does not automatically mean having a more organised portfolio.
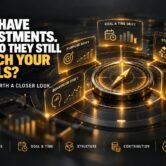
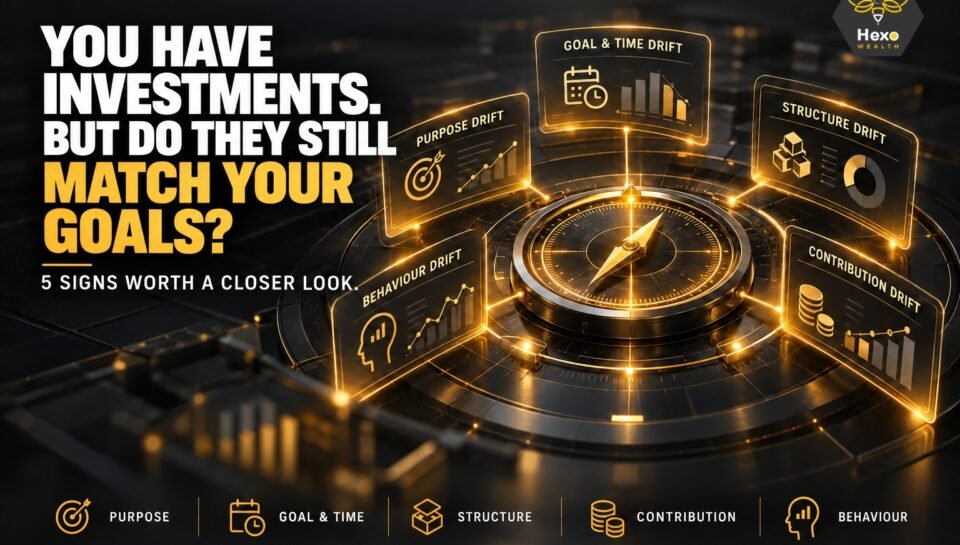
At Hexo, one useful way to think about this is through the 5-Drift Portfolio Check. Most portfolio problems begin when the purpose, timeline, structure, contribution or investor behaviour slowly moves away from where it started.
Here are 5 signs worth looking for:
1. You Have Multiple Mutual Funds but Cannot Explain the Purpose of Each:
This is Purpose Drift.
You may have six, eight or twelve mutual funds, but the fund count itself tells you very little. A more useful test is whether you can explain, in one sentence, why each significant holding exists.
For example:
- Fund A: Retirement, expected after 18 years
- Fund B: Child education, expected after 9 years
- Fund C: Long-term unassigned wealth
- Fund D: No longer sure why it was added
Fund D deserves attention even if its returns have been good.
A practical mutual fund portfolio analysis should therefore ask:
- What role does this investment perform?
- Which goal, if any, is it connected to?
- What category does it belong to?
- When may the money be required?
- Is another investment already performing the same job?
- Would I still include this fund if I were organising the portfolio today?
The problem is not necessarily having many mutual funds. The problem begins when the portfolio contains more fund names than clear reasons.
2. Your Financial Goals or Time Horizon Have Changed:
This is Goal & Time Drift.
An investment decision made seven years ago reflected the life you had seven years ago. Since then, income may have increased, a child may have been born, a home loan may have started, retirement expectations may have changed or an important goal may simply have moved closer.
Consider someone who originally invested for a goal fifteen years away. If that money is now expected to be used after four years, the mutual fund has not necessarily changed, but the job assigned to it has.
That is why how to review a mutual fund portfolio should not begin with:
“Which fund has performed best?”
It should begin with questions such as:
- What is this money now meant for?
- When will it actually be required?
- Can that deadline be postponed?
- How much of the future requirement has already been built?
- Does the existing investment structure still make sense for the remaining time?
A good investment can become a poor fit simply because the goal around it changed.
The portfolio review therefore needs to examine the investor’s life as well as the fund.
3. Your Portfolio Has Several Funds With Possible Overlap:
This is Structure Drift.
Holding several mutual funds can create the appearance of diversification even when the underlying investments are quite similar. Different schemes may repeatedly own the same companies, sectors or market segments.
A May 2026 analysis covering 561 pairs of large-cap funds found average weighted overlap of roughly 41%. That does not mean two funds with overlap must automatically be consolidated, but it shows why diversification cannot be judged simply by counting scheme names.
A useful mutual fund portfolio check should look at:
- Fund categories
- Common underlying holdings
- Sector concentration
- Market-cap exposure
- Equity/debt mix
- Role assigned to each scheme
- Overall asset allocation
Overlap itself is not a buy-or-sell signal.
For example, two funds may share some large companies but still have sufficiently different portfolio construction and roles. In another portfolio, four funds may be doing almost the same job without the investor realising it.
The better question is: “Is this overlap intentional, or did it happen simply because funds kept getting added?”
That is a much more useful way to think about portfolio diversification.
4. Your SIPs Are No Longer Connected to Your Current Financial Requirements:
This is Contribution Drift.
An SIP is automated, but the financial goal is not. The monthly debit may continue perfectly for ten years while the goal amount, income, existing corpus and time remaining all change around it.
India had more than 10.75 crore outstanding SIP accounts in August 2026, with monthly SIP contributions of ₹32,297 crore. Automation has clearly become a major part of mutual fund investing, but an active SIP does not automatically mean the contribution remains adequate for its original objective.
Suppose ₹25,000 has been invested every month for several years towards a child’s education.
A review should now ask:
- What could the education requirement be when needed?
- How much has already accumulated?
- What other assets are genuinely earmarked for that goal?
- How many years remain?
- Is the existing SIP still relevant to the possible gap?
- Is the current contribution still sustainable?
The answer may be that the SIP amount needs review. But it could equally be that existing investments already cover much more of the goal than expected.
The Hexo Portfolio Future Value Calculator can bring multiple existing assets and future contributions into one mathematical projection, including different starting values, contribution frequencies, investment tenures and Step-Ups. The result is an illustration based on assumptions, not a prediction of returns or an assessment that any particular allocation is suitable.
The useful question after the projection is not simply: “How much more should I invest?”
It is: “What, if anything, does the current gap actually require me to reconsider?”
5. You Are Making Investment Decisions Mainly Based on Recent Performance:
This is Behaviour Drift.
Recent returns are highly visible. Purpose, structure and suitability are much less exciting, which makes it easy to judge the portfolio through whichever fund is currently at the top or bottom of the return table.
Suppose one fund trails another for a period.
That does not immediately tell you whether:
- the entire category has been going through a weak phase,
- the scheme itself has behaved differently from relevant peers,
- the fund’s portfolio style is temporarily out of favour,
- or the investment no longer fits the purpose for which you hold it.
A proper mutual fund portfolio performance review therefore needs context.
Look at:
- Investment objective
- Fund category
- Appropriate benchmark
- Portfolio composition
- Risk characteristics
- Consistency across relevant periods
- Role within your overall portfolio
- Whether the original reason for owning the fund still exists
A falling market is not automatically a portfolio problem. Similarly, a fund delivering a strong recent return is not automatically evidence that it deserves a larger allocation.
The useful question is: “Has something materially changed, or am I simply reacting to recent numbers?”
Does a Portfolio Review Mean You Should Switch Your Mutual Funds?
No.
A portfolio review is a diagnosis. It is not an automatic instruction to repair something.
After completing the review, several outcomes are possible:
- No change: the existing fund still performs the role for which it was selected.
- Role clarification: the fund is retained but assigned more clearly to a particular objective.
- Contribution review: the portfolio structure may be fine, but the SIP amount may need reassessment.
- Structure review: overlap or concentration deserves a closer look.
- Goal remapping: the original objective or timeline has changed.
This distinction matters because frequent unnecessary switching can create its own complications, including exit loads, taxation and disruption of a long-term approach.
Sometimes the most useful result of a review is confirmation that nothing needs to be changed.
Where Does Portfolio Management Fit Into the Review?
Portfolio Management Services (PMS) and a mutual fund portfolio review are not the same thing.
PMS is a separate SEBI-regulated investment service provided by registered portfolio managers. The current regulatory framework specifies a minimum investment of ₹50 lakh for PMS clients.
A larger or more complex mutual fund portfolio does not automatically mean the investor should move to PMS. Whether any separate investment route deserves consideration depends on objectives, financial circumstances, risk profile, investment horizon and the characteristics of that product.
When Should You Review Your Mutual Fund Portfolio?
A portfolio does not need a fresh diagnosis every time the market falls 5% or one scheme moves down the rankings. A review becomes much more relevant when something meaningful changes.
Examples include:
- A major financial goal changes
- The goal moves materially closer
- Income changes significantly
- Marriage or childbirth changes responsibilities
- A new loan or liability is added
- Risk capacity changes
- Several funds have accumulated over time
- SIPs no longer appear connected to requirements
- The purpose of an existing fund is unclear
- A scheme’s characteristics change materially
There is no need to turn portfolio review into portfolio watching. The purpose is not activity. It is alignment.
What If You Are Not Sure Whether Your Portfolio Needs a Review?
Start with a simple self-check. If several answers are unclear, a review may be worthwhile:
- Can I explain why each major mutual fund is in my portfolio?
- Do I know which goal each investment supports?
- Has any important goal or timeline changed?
- Do several funds appear to perform similar roles?
- Do I know whether my existing SIPs are broadly connected to the requirement?
- Am I thinking about switching mainly because of recent performance?
- Can I explain what would actually need to change if the review found a problem?
The objective is clarity before action.
A review is useful when it tells you not only what you own, but whether those investments still have a reason to be there.
Review Your Mutual Fund Portfolio With a Goal-First Approach
The five signs in this article can be brought together through the Hexo 5-Drift Portfolio Check:
|
Drift |
Question to Ask |
|
Purpose Drift |
Can I explain why I own every important fund? |
|
Goal & Time Drift |
Has the job or deadline changed? |
|
Structure Drift |
Have overlap or concentration increased? |
|
Contribution Drift |
Are my SIPs still connected to the requirement? |
|
Behaviour Drift |
Am I reacting mainly to recent performance? |
This changes the purpose of a review.
Instead of searching immediately for funds to remove, start by identifying where the drift occurred. Only then decide whether any action is actually necessary.
For eligible investors, Hexo Wealth can review existing mutual fund holdings within its role as an AMFI-registered Mutual Fund Distributor, keeping the investor’s stated goals, investment horizon, risk profile and current mutual fund portfolio in view.
Hexo Wealth Associates LLP | Hiranandani Estate, Thane | AMFI-registered Mutual Fund Distributor | ARN 353817
Frequently Asked Questions:
A mutual fund portfolio review is an assessment of existing mutual fund holdings in the context of the investor’s goals, investment horizon, risk profile, portfolio structure and current circumstances.
Its purpose is to identify whether the portfolio still performs the roles for which it was built. It does not automatically require any investment to be sold or switched.
A review may be useful when goals, income, responsibilities, time horizon or risk capacity have changed. It can also help when several funds have accumulated and you are no longer clear about the purpose or overlap between them.
One useful test is whether you can explain both why you own each important fund and what would make you reconsider it.
No. A review can conclude that the existing portfolio remains suitable for the role it was meant to perform.
Other possible outcomes include reviewing contributions, clarifying fund roles, examining overlap or reassessing a changed goal. Switching is only one possible outcome, not the purpose of the review itself.
There is no universal number that automatically becomes “too many”. What matters is whether the funds perform distinct roles and whether their underlying exposures create unnecessary duplication.
Six clearly differentiated funds can be more organised than twelve schemes that repeatedly provide similar exposure.
A periodic review can be useful, but meaningful life or financial changes are often better triggers than short-term market movements.
Changes in goals, timelines, liabilities, income, responsibilities, risk profile or scheme characteristics may all justify a closer look.
Conclusion
A mutual fund portfolio review should not begin with the question: “Which fund should I remove?”
That starts too late in the process. Most portfolios need attention because something has gradually drifted: the purpose, goal, timeline, structure, contribution or investor behaviour.
So before changing an investment, diagnose the drift.
Purpose Drift. Goal & Time Drift. Structure Drift. Contribution Drift. Behaviour Drift.
Once you know which of these has changed, the next decision becomes much clearer.
Because a portfolio review is not about creating more activity. It is about understanding whether the investments you already own are still doing the jobs you expect them to do.
Disclaimer
This article is intended for general investor education and informational purposes only. It should not be treated as personalised investment advice, portfolio management advice, or a recommendation or solicitation to buy, sell, switch, continue or hold any particular mutual fund scheme, security, PMS product or other investment.
References to mutual fund portfolio review, mutual fund portfolio analysis, mutual fund portfolio check, mutual fund portfolio performance review, portfolio diversification and similar terms are used for educational purposes. Individual decisions depend on factors including stated financial goals, investment horizon, risk profile, liquidity requirements, existing investments, liabilities and personal financial circumstances.
Portfolio overlap, historical performance, benchmarks, projections and calculator results are individual data points or mathematical illustrations and should not be interpreted in isolation as instructions to buy, sell, retain or switch any investment. Past performance does not guarantee future performance.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor, ARN 353817, and may receive commissions from Asset Management Companies on investments made under Regular Plans. Hexo Wealth is not presented in this article as a SEBI-registered Portfolio Manager or Investment Adviser.