
Financial Planning for Salaried Employees: A Practical Goal-Based Approach
A salary has one very convenient feature. It usually arrives every month.
Your EMI gets deducted. Household expenses are paid. Insurance continues. An SIP may go out automatically. EPF is building in the background. You may also have fixed deposits, savings and other investments.
So financially, things can appear organised. But there is a more important question: Are all these monthly money movements actually taking you closer to the future you are preparing for?
That is where financial planning for salaried employees, used here as an educational concept, becomes more useful than simply deciding how much of your salary to save.
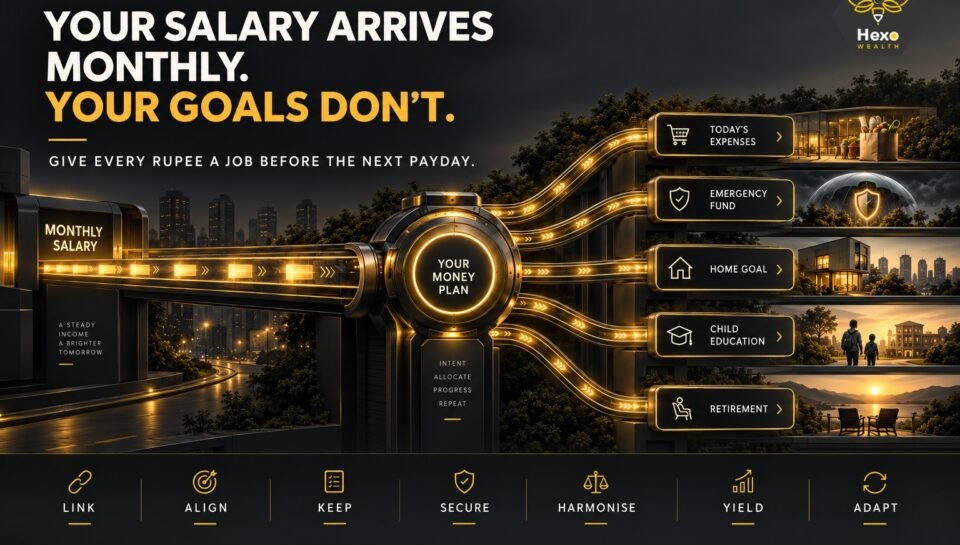
A salary is monthly. Your goals are not.
A home down payment may need ₹30 lakh on one date. Your child’s higher education could require money over four years. Retirement eventually replaces decades of monthly salary. Emergencies rarely arrive conveniently after the next payday.
The objective, therefore, is not simply to invest more. It is to connect a predictable monthly income with financial requirements that may arrive at very different points in life.
Start With What Your Money Needs to Do
The easiest way to begin investing is to ask: “Which mutual fund should I choose?” Or: “How much SIP should I start?”
The more useful starting point is to ask what your salary needs to achieve beyond paying this month’s bills. For most salaried households, money has several jobs running simultaneously.
1) Immediate responsibilities:
These include regular household expenses, EMIs, insurance premiums and other commitments that cannot simply be postponed.
2) Nearer financial goals:
These may include a home down payment, a planned major purchase, family requirements or another expense expected over the next few years.
3) Longer-term goals:
Child education, retirement and long-term wealth requirements may be many years away, but delaying them completely can make the eventual funding requirement harder.
This is what makes financial planning for salaried professionals more nuanced than choosing one investment percentage for everyone.
Two colleagues may both take home ₹1.5 lakh per month. One may be single, have no EMI and already hold significant savings. The other may have a home loan, dependent parents and two young children.
Their salaries are identical. Their money does not have the same jobs. That is why the goal should come before the investment.
Understand Your Salary Before Deciding How Much to Invest
Take-home salary by itself does not tell you how much you can genuinely invest.
Suppose your monthly salary is ₹1.5 lakh and your normal monthly expenses total ₹1.05 lakh. It may appear that you have ₹45,000 available every month. But what if the household also has:
- ₹60,000 of annual insurance premiums
- ₹1.2 lakh of annual school-related expenses
- ₹60,000 of expected home and vehicle maintenance
- ₹1.2 lakh budgeted for travel and family commitments
Those four expenses total ₹3.6 lakh a year, which is another ₹30,000 per month when viewed properly. The apparent ₹45,000 surplus now looks very different. This gives us an important distinction.
-
Monthly Surplus: What remains after the expenses visible in a normal month.
-
True Usable Surplus: What remains after also providing for predictable annual and irregular commitments.
That second number is far more useful when deciding how much of your salary can realistically be committed to long-term investing.
A practical salary map could therefore look like: Take-home salary → Essential expenses → EMIs → Insurance → Annual expenses converted monthly → Existing commitments → Available surplus
There is no requirement to follow a universal 50:30:20 formula. Rules can be useful as starting points, but financial planning for salaried individuals becomes more meaningful when the numbers reflect the actual household.
Build a Financial Cushion for Unexpected Expenses
A regular salary can create a feeling of financial stability. But the household commitments that depend on that salary do not disappear if the income temporarily stops. The home EMI still arrives. School fees still arrive. Groceries, utilities and insurance still need to be paid.
That is why an emergency reserve is not simply another investment bucket. Its job is to prevent a temporary income disruption or unexpected expense from forcing you to disturb money meant for long-term goals.
The amount does not have to be based blindly on one fixed rule.
Consider:
- Essential monthly household expenses
- EMIs and mandatory debt repayments
- Number of dependants
- Stability of employment
- Ease of finding similar employment if required
- Number of earning members in the household
- Health and other insurance
- Existing accessible savings
A dual-income household with low liabilities and stable employment may need a different cushion from a single-income household carrying a large EMI and supporting dependants.
Recent discussion around emergency reserves has increasingly moved away from treating one fixed number of months as suitable for everybody. Job stability, household obligations and income concentration materially change the requirement.
The purpose of the emergency reserve is simple. Long-term money should not have to solve a short-term financial shock.
Calculate the Future Cost of Your Goals
Today’s price tag is rarely the number you should build towards for a goal that is many years away.
Suppose a child’s higher education course costs ₹20 lakh today. If the goal is twelve years away, the illustrative future cost would be around:
|
Assumed annual cost increase |
Approximate future cost after 12 years |
|
6% |
₹40.2 lakh |
|
8% |
₹50.4 lakh |
|
10% |
₹62.8 lakh |
These are mathematical illustrations, not predictions. But notice what changes. The same goal can produce materially different future requirements depending on the assumptions used. That means the useful sequence is: Current cost → Time available → Inflation assumption → Estimated future requirement
Once that future requirement is clearer, connect it to what you already have and what your salary can reasonably fund over time. This is also where salaried households should avoid one common mistake.
Do not assume that every goal will grow at the same rate or arrive at the same time. Education, housing, retirement and lifestyle expenses each have their own timelines and uncertainties. The job is not to predict the future perfectly. It is to make today’s decisions with a clearer view of what the future may demand.
Look at What You Already Own Before Adding Another Investment
Salaried employees often accumulate investments in layers.
EPF begins through employment. A PPF account may have been opened years ago. NPS may come through the employer or individual contribution. An SIP gets started. An FD is created after a bonus. Insurance policies sit separately.
A few years later, the household owns many financial products but may not have one clear view of what each one is meant to do.
Before asking: “What should I invest in next?” ask: “What job does each investment already perform?”
A simple map can help:
|
Goal |
When required |
Existing resources |
Estimated future requirement |
Possible gap |
|
Child education |
Year X |
Goal-linked savings/investments |
₹X |
₹X |
|
Home purchase |
Year X |
Dedicated savings/mutual funds |
₹X |
₹X |
|
Retirement |
Year X |
EPF, NPS, retirement-linked investments, mutualfunds |
₹X |
₹X |
The table may reveal something important.
You may not actually need another investment product. You may first need to reorganise how the existing investments are being counted.
The same ₹10 lakh portfolio cannot simultaneously fund a home, education and retirement in full. Owning money and allocating money are not the same thing.
What If Your Current Investments Are Not Enough?
Finding a funding gap is useful information.
It does not automatically mean: Invest much more immediately. And it certainly does not automatically mean: Take more investment risk.
A gap gives you several possible levers:
1) Increase the contribution:
If the household genuinely has more available surplus, the monthly investment can be reconsidered.
2) Use future salary growth:
A salaried employee has one advantage that is often underused: income may rise over the career. That future income can gradually increase the contribution instead of forcing today’s salary to carry the entire future requirement.
3) Use bonuses carefully:
A bonus is different from salary. Because it is not necessarily recurring, it may be better evaluated as a possible one-time contribution rather than using it to create a permanent monthly commitment.
4) Review the goal:
Some goals have flexible dates, amounts or funding responsibilities. Others do not. The goal itself may therefore be one of the variables.
5) Review existing investments:
The problem may not always be the amount invested. There may already be resources sitting outside the goal calculation, or there may be unnecessary duplication inside the existing portfolio. This is where the Hexo SIP Calculator becomes particularly relevant for a salaried investor.
It can model a current portfolio, monthly SIP, annual SIP step-up, future one-time investments such as bonuses and planned future withdrawals in one illustration. This makes it possible to test how the investment journey could change as salary and contributions change, rather than assuming the current SIP will remain fixed forever. The output remains an assumption-based illustration, not a forecast or assurance of future returns.
Choose the Investment Approach After Understanding the Goal
Once the goal, requirement, existing resources and possible gap are clearer, investment options become easier to evaluate. A requirement expected after two years should not automatically be approached in the same way as retirement twenty-five years away.
The relevant questions are:
- When will the money be required?
- How important is the goal?
- Can the goal be postponed?
- How much investment fluctuation can the household tolerate?
- What assets are already held?
- How much liquidity is required?
- What other financial responsibilities exist?
Asset allocation then becomes a consequence of those answers rather than a generic percentage copied from somewhere else.
A household may have exposure across equity, debt, cash, real estate, gold and other assets. There is no one asset allocation that automatically suits every salaried employee.
The goal determines the job. The investment route should be evaluated for that job.
Where Do SIP, EPF, NPS and PPF Fit?
One of the easiest mistakes in personal finance is turning product names into goals.
- EPF is not a goal.
- NPS is not a goal.
- PPF is not a goal.
- An SIP is not a goal either.
They are different ways in which money may be accumulated or invested, each with its own structure, rules and characteristics.
For a salaried person:
- EPF may form part of longer-term retirement resources where applicable.
- NPS is structured around retirement and has its own contribution, withdrawal and tax rules.
- PPF may form part of longer-term savings, subject to its rules and tenure.
- SIPs are a method of investing periodically into mutual funds and can be considered for suitable goals depending on time horizon, risk profile and circumstances.
- Fixed deposits and bank savings may play a role where accessibility or stability is important.
The useful question is not: “Which one is best?” It is: “Which financial requirement is this money meant to support?”
One product does not have to perform every job.
Tax Planning Should Not Replace Financial Planning
Tax-saving season can easily change the order of decision-making. Instead of asking what the money needs to do, the question suddenly becomes: “March aa gaya. Tax bachane ke liye kahan invest karein?”
Tax matters, but a tax benefit should not convert an unsuitable investment into a suitable one.
For AY 2026-27, the new tax regime remains the default regime, while eligible taxpayers can choose the old regime where applicable. The deductions and exemptions available differ between the two regimes.
So before making a tax-led investment decision, check:
- Which tax regime applies to you?
- Is the particular deduction or exemption actually available?
- Would the investment still make sense without the tax benefit?
- What is its investment horizon?
- What liquidity restrictions apply?
- What risk is involved?
- Does the money already have another more important job?
Tax efficiency can support a good money decision. It should not create a bad one. Individual tax decisions should be checked against the rules applicable for the relevant year and, where necessary, with an appropriate tax professional.
Retirement Needs More Than a Last-Minute SIP
Retirement is unusual because there is no single bill waiting at the end. There may instead be twenty or thirty years during which the salary no longer arrives but household expenses continue. That means retirement should not be reduced to: “I already have EPF and one SIP. It should be fine.”
A more useful retirement check looks at:
- Expected retirement age
- Current lifestyle expenses
- Future expenses after inflation
- Existing retirement-linked resources
- Other income that may continue
- Healthcare and liquidity requirements
- Expected retirement duration
- Possible retirement funding gap
The earlier this becomes visible, the greater the number of variables you may still be able to adjust.
Starting later does not automatically mean failure. It simply means time can no longer do as much of the work, so the contribution, retirement date, lifestyle assumption or other parts of the equation may need closer attention.
For a salaried professional, retirement is ultimately the point at which the assets accumulated over the working years gradually need to take over part of the financial work previously performed by salary.
Review Your Plan as Your Life Changes
For salaried employees, the annual appraisal cycle creates a natural financial review point. But a salary hike should not automatically mean: “Increase every SIP by 10%.”
Sometimes that may make sense. Sometimes it may not.
Suppose your salary increases by ₹20,000 a month.
During the same year, you may also have:
- A new home EMI
- Childcare expenses
- Ageing-parent responsibilities
- Higher insurance premiums
- A goal whose deadline has moved closer
- An emergency reserve that is still incomplete
The increase in salary should therefore trigger a review, not an automatic formula.
Ask:
- What changed in my income?
- What changed in my expenses?
- What changed in my goals?
- Which goal has the biggest gap?
- Which existing investment can simply be increased instead of adding another product?
Recent 2026 discussion around salary hikes has also focused heavily on reviewing and increasing SIPs as income rises, but the contribution decision still needs to reflect the investor’s actual circumstances.
Other events deserve the same review:
- Promotion
- Job change
- Marriage
- Childbirth
- Home purchase
- Major debt repayment
- Significant bonus
- Change in dependants
- Approaching a major goal
An old investment decision does not automatically remain appropriate simply because the auto-debit still works.
A Simple Framework to Keep Your Financial Goals on Track
For a salaried professional, LAKSHYA can bring the salary, goals and investments into one connected view.
L: Link
Link money to the goal.
Do not let the salary simply flow from account to expenses to random investments every month. Identify what the money is being accumulated for.
A: Align
Align the investment with the amount, timeline and risk involved.
A five-year requirement and a twenty-five-year retirement goal do not need to be approached identically.
K: Keep
Keep contributions moving with the goal.
A salary may grow over the years. The contribution should be periodically checked against the updated future requirement rather than remaining unchanged indefinitely.
S: Secure
Secure the base before stretching for growth.
Emergency liquidity, insurance and unavoidable commitments matter because a long-term investment works best when it does not repeatedly need to be disturbed for short-term shocks.
H: Harmonise
Harmonise today’s lifestyle with tomorrow’s requirements.
The objective is not to stop enjoying the salary today. It is to prevent every salary increase from being absorbed permanently into lifestyle before future goals receive their share.
Y: Yield
Give long-term investments the time their role requires.
Market-linked investments need to be understood with their associated risks and without assuming or assuring any particular future return.
A: Adapt
Adapt as salary and life change.
A goal-based approach created at age thirty should not remain frozen at forty merely because the original SIPs are still running.
That is the practical idea behind LAKSHYA.
Your salary is the monthly input. Your goals are the destination. The investments sit between the two.
Frequently Asked Questions:
Used educationally, financial planning for salaried employees means organising income, expenses, savings and investments around future financial requirements. A practical approach starts by understanding cash flow, defining goals, estimating future requirements, reviewing existing resources and then evaluating how possible gaps may be addressed.
There is no universal percentage. The amount depends on take-home income, essential expenses, annual commitments, EMIs, dependants, emergency reserves, existing investments, financial goals and the time available for those goals.
A percentage rule can be a starting reference, but the better number is the amount that is both sustainable today and connected to an actual future requirement.
An SIP is only a method of investing periodically in a mutual fund. It does not by itself determine whether the amount is sufficient for a particular goal, whether adequate emergency liquidity exists or whether another financial priority needs attention first.
The SIP should therefore be viewed in the context of the purpose, time horizon, existing resources and risk profile.
There is no one number suitable for every household. Essential expenses, EMIs, dependants, job stability, number of income earners, insurance and liquid savings all affect the requirement.
The purpose is to maintain enough accessible money so that a temporary financial shock does not unnecessarily disturb long-term investments.
A salary increase is a good time to review your complete money picture. Before automatically increasing spending or investments, check whether your emergency reserve, liabilities, near-term goals and long-term contribution requirements have also changed.
Where a larger SIP is appropriate, the increase can then be connected to a defined goal rather than simply following a fixed percentage.
Take the Next Step With Greater Clarity
A salary can make money feel predictable. But the biggest financial requirements in life rarely arrive in predictable monthly instalments. That is why a good goal-based approach should connect 3 things:
- What comes in today.
- What life requires today.
- What future goals may require tomorrow.
LAKSHYA brings those pieces into one view by linking money to goals, aligning investments with the requirement, keeping progress under review and adapting as life changes.
For investors whose goal-linked approach includes mutual funds, Hexo Wealth can support eligible mutual fund investments and review existing mutual fund holdings based on the investor’s stated goals, investment horizon, risk profile and individual circumstances.
Hexo Wealth Associates LLP | Hiranandani Estate, Thane | AMFI-registered Mutual Fund Distributor | ARN 353817
Disclaimer
This article is intended solely for investor education and general information. It should not be treated as personalised investment, financial, retirement, tax or legal advice, detailed financial planning, or as a recommendation to invest in any particular mutual fund scheme or financial product.
The phrases Financial Planning for Salaried Employees, financial planning for salaried professionals, financial planning for salaried individuals, personal financial planning and related terms are used in an educational context to explain how salaried individuals may organise income, expenses, savings, investments and financial goals. They should not be interpreted as representing Hexo Wealth as a SEBI-registered Investment Adviser or provider of comprehensive financial-planning services.
Mutual fund suitability depends on the investor’s stated objectives, investment horizon, risk profile and individual circumstances. Calculator results and examples are mathematical illustrations based on assumptions and do not represent a forecast, assurance or guarantee of investment returns or achievement of any financial goal.