
How to Select Mutual Funds Based on Your Financial Goals
Choosing a mutual fund can become confusing very quickly.
You open an investment platform and see hundreds of schemes. One fund has delivered strong recent returns. Another has five stars. One has a lower expense ratio. Another is currently popular. A colleague recommends a different one altogether.
The natural question becomes: “Which mutual fund should I choose?”
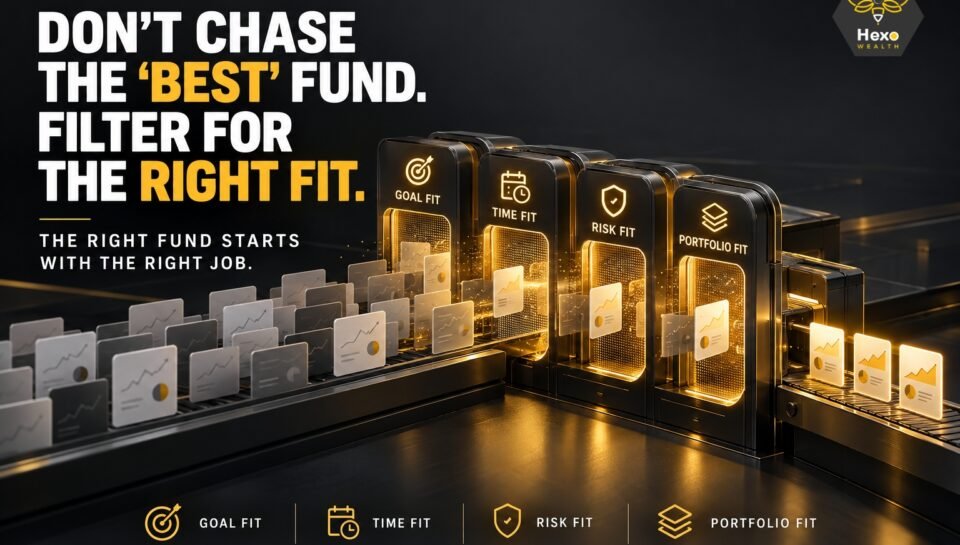
But there is an easier way to approach the problem. You do not need to find the “best” mutual fund out of every scheme available. You first need to eliminate the funds that do not fit what your money is meant to do. That changes mutual fund selection from a ranking exercise into a filtering exercise.
If you are trying to understand how to select mutual funds, start with four questions:
- What is this money for?
- When may I need it?
- How much investment risk can this goal reasonably take?
- What investments do I already own?
Only after those questions should the individual scheme enter the conversation.
A good mutual fund can still be the wrong mutual fund for your portfolio.
Start With Your Financial Goal
Before comparing schemes, give the money a job. The goal could be:
- Retirement
- Child education
- Buying a home
- A major future family requirement
- Long-term wealth creation
- Another defined financial objective
This matters because different goals have different consequences if the money is not available when required. For example, retirement twenty years away and a house down payment three years away should not automatically be approached through the same type of mutual fund.
So instead of beginning with: “Which mutual fund should I invest in?” begin with: “What exactly is this investment expected to do?”
This is the first filter in understanding how to choose mutual funds for financial goals.
Estimate Your Future Financial Requirement
Once the purpose is clear, put an approximate number around it. Suppose higher education costs ₹20 lakh today but the requirement is ten years away. The amount needed later could be materially different because the cost itself may rise over time.
For a long-term goal, consider:
- Current cost
- Time remaining
- Reasonable inflation assumption
- Existing goal-linked investments
- Future contributions
- How much of the total requirement you personally intend to fund
The result does not need to be treated as a prediction. Its purpose is to answer a simpler question:
Are you investing towards a ₹20 lakh problem, ₹50 lakh problem or ₹1 crore problem?
The size of the requirement can affect the contribution needed, but it should not tempt you into choosing a higher-risk fund simply because the projected gap looks large. A funding gap and risk capacity are two separate questions.
Review Your Existing Investments First:
Before adding another mutual fund, look at what is already in the portfolio. You may have:
- Mutual funds
- Existing SIPs
- EPF
- PPF
- NPS
- Fixed deposits
- Bank savings
- Other investments
But simply listing them is not enough. For every mutual fund already held, ask:
- Why do I own this fund?
- Which goal is it expected to support?
- What category does it belong to?
- Does another fund already perform a similar role?
- Would I still add this fund today if I were rebuilding the portfolio from scratch?
That final question can be surprisingly useful.
Many portfolios become complicated not because every fund is poor, but because funds were added at different points without checking what was already present.
The result may be ten perfectly respectable funds doing the work that four or five could have done more clearly.
Match the Investment With Your Time Horizon:
The next filter is time. Ask: When might this money actually be required?
A near-term requirement has less time to recover from substantial market fluctuations. A long-term goal may have more time, but that does not automatically mean the highest-risk category should be selected.
Think of goals broadly as:
1) Near-term goals: money may be required relatively soon. Liquidity and capital stability usually deserve greater attention.
2) Medium-term goals: there may be some capacity for market-linked exposure, but the exact investment approach needs to reflect how important and flexible the goal is.
3) Long-term goals: a longer period can provide more time to participate in market cycles, but the appropriate category still depends on the investor’s risk profile and existing portfolio.
There is one additional question that is often more useful than simply asking whether the goal is three years, seven years or fifteen years away: Can I postpone this goal if markets are unfavourable when the money is required?
A vacation may be postponed. A child’s college admission may not be. The deadline matters, but the flexibility of the deadline matters too.
Understand Your Risk Profile:
Risk is often reduced to a questionnaire that labels someone:
- Conservative.
- Moderate.
- Aggressive.
But selecting mutual funds based on risk profile requires a little more thought.
Consider:
- Ability to tolerate market fluctuations
- Stability of income
- Existing liabilities
- Dependants
- Emergency liquidity
- Investment horizon
- Importance of the goal
- Other assets already held
- How you are likely to behave during a meaningful market decline
SEBI’s current Risk-o-meter framework classifies mutual fund schemes across six risk levels, from Low to Very High, and the scheme’s Risk-o-meter is evaluated periodically. That is useful information. But the Risk-o-meter tells you about the scheme’s risk, not whether that level of risk is suitable for your goal. Both sides need to fit.
Choose the Mutual Fund Category Before the Scheme
This is where the selection process becomes much simpler.
Do not begin by comparing Fund A with Fund B. First determine what type of mutual fund deserves consideration. Depending on the investor’s circumstances, this could involve evaluating equity-oriented, debt-oriented, hybrid or other permitted mutual fund categories.
The sequence should ideally be: Goal → Future Requirement → Time Horizon → Risk Profile → Existing Portfolio → Fund Category → Scheme
Here’s why does this matter:
Imagine someone comparing:
- a flexi-cap fund
- a mid-cap fund
- an aggressive hybrid fund
All three may have strong historical numbers.
But that does not make them interchangeable. They are built differently and may carry different portfolio characteristics and levels of risk. So the first question is not: “Which of these gave the highest return?” It is: “Which category is actually being considered for this job?”
Only then does scheme comparison become meaningful.
Look Beyond Recent Performance:
Once the appropriate category has been narrowed down, individual schemes can be evaluated. Recent returns may be one data point, but they should not become the entire selection process.
A stronger scheme-level check includes:
-
Investment objective: what is the scheme actually trying to do?
-
Portfolio composition: where is the money currently invested? Is the portfolio concentrated in particular companies, sectors or segments?
-
Risk characteristics: what does the current Risk-o-meter indicate, and is that consistent with the role the fund is expected to play?
-
Consistency: how has the scheme behaved across different market periods rather than only during the strongest recent phase?
-
Costs: the Total Expense Ratio affects the NAV of a mutual fund scheme and is an important scheme characteristic to understand.
But cost should be evaluated in context. A fund does not become appropriate merely because its expense ratio is lower.
Role in your portfolio:
This may be the most overlooked question: What does this fund add that my existing portfolio does not already have?
AMFI factsheets themselves provide information such as investment objective, benchmark, expense ratio, portfolio holdings and quantitative risk measures. The objective is not to collect the maximum number of metrics. It is to understand the scheme well enough to know why it belongs in the portfolio.
Check for Overlap in Your Portfolio:
More mutual funds do not automatically create more diversification. Two funds with different names may still own several of the same companies or provide very similar market exposure.
Before adding another scheme, review:
- Existing fund categories
- Common holdings
- Sector exposure
- Market-cap exposure
- Overall concentration
- The purpose assigned to each fund
For example, if two funds have substantial common holdings, that does not automatically mean one must be removed.
Overlap is a diagnostic measure, not a buy-or-sell instruction.
The useful question is: Is this overlap intentional, or did it happen because funds kept getting added without reviewing the portfolio?
A smaller portfolio where every fund has a clear role can sometimes be easier to understand and monitor than a larger collection with repeated exposures.
Calculate the Potential Funding Gap
Once you know the future requirement and the resources already assigned to the goal, you can estimate the potential gap.
Suppose:
|
Item |
Amount |
|
Estimated future requirement |
₹50 lakh |
|
Existing goal-linked resources |
₹15 lakh |
|
Potential gap |
₹35 lakh |
That ₹35 lakh does not tell you which mutual fund to buy. It tells you the amount the future contribution may need to address under the assumptions used.
The Hexo SIP Calculator can then illustrate how an existing portfolio, monthly SIP, Step-Up SIP, future lumpsum investments and planned withdrawals may interact over the selected period.
For example, the investor can compare what happens when:
- the monthly contribution changes
- the SIP is increased over time
- a future bonus is invested
- an existing portfolio is included
- money is withdrawn for another planned requirement
The result remains a mathematical illustration. It does not determine which mutual fund is suitable or guarantee that the goal will be achieved.
Review Your Mutual Fund Selection Periodically
A mutual fund should not be changed merely because another fund has recently performed better.
At the same time, “long term” should not mean “never review”. A review may become relevant when:
- The financial goal changes
- The goal moves closer
- Income changes materially
- Marriage or childbirth changes responsibilities
- A new liability is added
- Risk capacity changes
- The existing portfolio becomes concentrated
- The fund’s investment role changes
- The scheme’s characteristics materially change
A useful review should therefore ask two different questions.
1) Has anything changed in my life?
This includes goals, timelines, liabilities, income and financial responsibilities.
2) Has anything materially changed in the investment?
This includes the fund’s role, portfolio characteristics, category fit and relevant risk information.
A review does not automatically mean selling or switching. Sometimes the correct conclusion after reviewing a fund is simply: It still does the job it was selected to do.
A Simple Framework for How to Select Mutual Funds
The entire process can be simplified through what we call the Hexo Fund Fit Filter. Before comparing schemes, check whether the investment clears 4 basic fits.
1. Goal Fit:
What is the money expected to achieve?
Without a clear role, even a good fund can become difficult to evaluate.
2. Time Fit:
When might the money be required?
The investment category should respect the time available and how flexible the goal is.
3. Risk Fit:
Can both you and the goal tolerate the level of uncertainty involved?
Investor risk tolerance alone is not enough. The importance and deadline of the goal also matter.
4. Portfolio Fit”
Does the fund add something useful to what you already own?
Look at category, holdings, concentration and overlap before introducing another scheme.
Once all 4 are reasonably clear, move to the individual scheme and review:
- Investment objective
- Portfolio composition
- Risk-o-meter
- Relevant costs
- Consistency
- Role within the complete portfolio
So the process becomes: Goal → Category → Scheme not: Returns → Rating → Fund name.
This is the biggest shift in understanding how to select mutual funds.
Need Help With Mutual Fund Selection?
Selecting mutual funds does not have to mean finding the most popular scheme or building a long list of funds.
For eligible investors, Hexo Wealth, as an AMFI-registered Mutual Fund Distributor, can support the mutual fund investment process by understanding the investor’s stated goal, time horizon, risk profile and existing mutual fund holdings before facilitating investments in Regular Plan mutual fund schemes.
The starting point remains simple: Understand the job first. Then evaluate the fund for that job.
Hexo Wealth Associates LLP | Hiranandani Estate, Thane | AMFI-registered Mutual Fund Distributor | ARN 353817
Before comparing schemes, give the money a job. The goal could be:
- Retirement
- Child education
- Buying a home
- A major future family requirement
- Long-term wealth creation
- Another defined financial objective
This matters because different goals have different consequences if the money is not available when required. For example, retirement twenty years away and a house down payment three years away should not automatically be approached through the same type of mutual fund.
So instead of beginning with: “Which mutual fund should I invest in?” begin with: “What exactly is this investment expected to do?”
This is the first filter in understanding how to choose mutual funds for financial goals.
Frequently Asked Questions:
Start by defining the goal and when the money may be required. Then consider the future requirement, existing investments, risk profile and appropriate fund category before comparing individual schemes.
This prevents recent performance from becoming the starting point of the decision.
Consider both sides of risk: the scheme’s characteristics and your own circumstances.
Your ability to tolerate fluctuations, investment horizon, liabilities, liquidity, goal importance and likely behaviour during market declines can all affect the decision. The scheme’s Risk-o-meter can provide additional information about its current risk classification.
No. Past performance is only one piece of information and does not guarantee future performance.
The scheme’s objective, category, portfolio, risk characteristics, costs, consistency and role in your existing portfolio should also be understood.
Possibly, but the number of funds itself does not create diversification.
Several funds may hold similar securities or provide similar exposure. The better question is whether every fund performs a distinct and useful role within the portfolio.
The purpose is to maintain enough accessible money so that a temporary financial shock does not unnecessarily disturb long-term investments.
No. Expense ratio is an important scheme characteristic because costs affect NAV, but it should not be used in isolation.
The first requirement is that the category and scheme fit the investor’s goal, horizon, risk profile and portfolio. Cost can then form part of the comparison among relevant alternatives.
Conclusion
Understanding how to select mutual funds becomes easier once you stop trying to identify the single “best” fund.
The real process is one of elimination.
Remove the categories that do not fit the goal. Remove risk that the goal cannot reasonably take. Remove funds that unnecessarily repeat what you already own. Then compare schemes that have actually earned the right to be considered.
A simple sequence is: Goal Fit → Time Fit → Risk Fit → Portfolio Fit → Category → Scheme
That is more useful than beginning with last year’s return table. Because a mutual fund does not become right for you simply because it is a good fund. It becomes relevant only when it has the right job in your portfolio.
Disclaimer
This article is intended solely for investor education and general information. It should not be treated as personalised investment, financial, tax or legal advice, or as a recommendation to invest, redeem, switch, continue or avoid any particular mutual fund scheme or security.