
SIP Mistakes Beginners Make When Starting Mutual Fund Investments
Starting an SIP has become one of the simplest ways to begin investing in mutual funds. In August 2026 alone, monthly SIP contributions in India reached ₹32,297 crore, with more than 10 crore contributing SIP accounts. That convenience can also create a blind spot. Once the automatic debit starts happening every month, it is easy to feel that the investment is taken care of, even when the amount, fund, timeline or purpose has never really been checked.
A SIP is a method of investing periodically into a mutual fund scheme. It is not an investment strategy by itself.
A successful monthly debit tells you that the transaction happened. It does not tell you whether the investment is right for what you are trying to achieve.
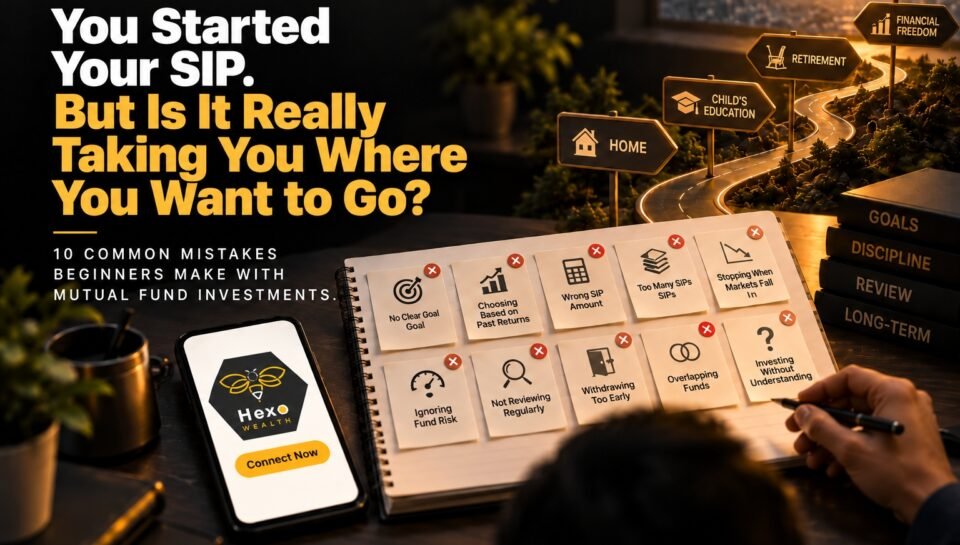
Here are 10 SIP mistakes beginners should avoid:
1. Starting a SIP Without a Clear Financial Goal:
A very common starting point is, “I should invest ₹5,000 every month,” rather than, “What am I building this ₹5,000 towards?” The SIP then runs for a few years, but when the investor eventually needs money for a home, education or another requirement, there is no clear connection between the investment and the expense.
Give the SIP a job before worrying about the fund name. That job could be retirement, a child’s higher education or another long-term requirement, but defining it helps answer the next questions: how long the investment may continue, how much may eventually be required and what level of investment risk can reasonably be considered.
The mistake is not starting small. It is starting without knowing what the money is supposed to become.
2. Choosing Mutual Funds Only Based on Recent Returns:
Imagine seeing two funds on a comparison page. One has delivered noticeably higher recent returns, so it immediately looks like the better SIP.
But the number tells you what happened during that period, not whether the scheme belongs in your portfolio. Mutual funds can differ in objective, underlying assets, portfolio concentration and risk, and past performance does not guarantee future performance.
Before choosing a fund because it is near the top of a return table, look at its investment objective, category, portfolio and Riskometer, then ask whether those characteristics fit the goal and time available. The Riskometer itself ranges from low to very high risk and is intended to help investors understand the risk level associated with a scheme.
A high recent return may get your attention. It should not complete the decision.
3. Investing Without Understanding the Required SIP Amount:
Another beginner pattern is choosing an amount because it feels comfortable: ₹2,000, ₹5,000 or ₹10,000 every month. There is nothing wrong with starting with an affordable amount, but affordability and adequacy are two different questions.
Suppose ₹5,000 is being invested towards a goal twelve years away. Whether that amount is meaningful depends on the possible future requirement, money already accumulated and the time available, not simply on whether ₹5,000 fits comfortably into this month’s salary.
The Hexo SIP Calculator can illustrate different scenarios by bringing together an existing portfolio, monthly SIP, Step-Up SIP, future lumpsum investments and planned withdrawals. Its outputs are mathematical illustrations based on the assumptions entered and are not forecasts or guaranteed mutual fund returns.
The better question is not only, “How much can I start with?”
It is also, “What is this amount expected to work towards?”
4. Starting Too Many SIPs:
This mistake usually does not happen deliberately. One SIP is started after a colleague recommends a fund, another after a salary hike, another after reading about a new category, and eventually five monthly debits appear on the bank statement.
Five SIPs do not automatically mean five different sources of diversification. Different schemes may own several of the same securities or create similar market exposure, so the number of funds can increase much faster than the number of genuinely different roles in the portfolio.
Instead of asking, “How many SIPs do I have?”, ask:
- What role does each fund perform?
- Are two or more funds doing substantially similar jobs?
- Which goal is each investment connected with?
- What does this fund add to what I already own?
More SIPs can make a portfolio look diversified while quietly making it harder to understand.
5. Stopping SIPs Because Markets Fall:
For a first-time investor, seeing the portfolio turn red while another monthly instalment is about to be debited can feel uncomfortable. The instinct may be to stop the SIP until markets “become normal again”.
But there is an important distinction beginners often miss: stopping an SIP stops future instalments. It does not automatically redeem the mutual fund units already accumulated. Those existing units remain invested unless a separate redemption transaction is made.
A market fall alone should therefore not become an automatic stop signal. Review whether the goal, investment horizon, financial circumstances or ability to take risk has actually changed before deciding what action is required.
There can absolutely be valid reasons to pause or stop an SIP, including cash-flow pressure or a changed financial requirement. The mistake is allowing the colour of today’s portfolio screen to make the decision by itself.
6. Expecting SIPs to Guarantee Returns:
An SIP may look similar to another monthly savings habit because a fixed amount leaves your bank account on a regular date. That similarity can create the incorrect expectation that the final outcome is also fixed.
It is not. An SIP simply determines how you invest into the mutual fund. The underlying mutual fund remains market-linked, its NAV can move up or down, and neither a particular return nor achievement of a financial goal is guaranteed.
Two people can both invest ₹10,000 per month through SIPs but experience very different outcomes if their underlying schemes, investment periods and market conditions differ.
Think of the SIP as the route through which the money enters the investment, not as a return promised at the destination.
7. Ignoring the Investment Horizon:
A monthly SIP can make an investment feel gradual and therefore safer, but the investment method does not change the characteristics of the mutual fund underneath it.
Someone investing for retirement twenty years away and someone needing education money after three or four years have very different timelines. Using the same mutual fund approach simply because both investors are using SIPs can create a mismatch between when the money is needed and how much investment fluctuation the goal can reasonably tolerate.
So before starting the SIP, ask when the money may actually be required. Then consider the scheme’s objective and risk in the context of that timeline.
An SIP spreads your investments over time. It does not turn a higher-risk mutual fund into a low-risk short-term investment.
8. Never Reviewing Your SIPs:
“Start and forget” can be useful for avoiding unnecessary daily interference, but it should not become “start and never look again”.
Over several years, the goal may change, the deadline may move closer, responsibilities may increase and the scheme itself may no longer play exactly the same role it did when the SIP began. A review is therefore not about finding reasons to switch every year, but about checking whether the original investment logic still holds.
Review questions can include:
- Is the goal still the same?
- Is the remaining horizon still appropriate?
- Does the fund still perform a useful role?
- Has portfolio overlap increased?
- Have my financial circumstances or risk capacity materially changed?
A good review can also end with a very simple conclusion: nothing needs to change.
9. Not Reviewing SIP Amounts as Income Changes:
The fund can remain appropriate while the SIP amount becomes outdated.
Someone may have started a ₹5,000 SIP when earning ₹50,000 per month and continue exactly the same contribution after income increases substantially. At the other extreme, responsibilities may increase and make an earlier SIP amount uncomfortable to sustain.
This is why contribution reviews should not simply mean “increase SIP by 10% every year”. A Step-Up can be useful where financially appropriate, but the decision should reflect changes in income, expenses, goals, existing investments and other responsibilities.
Sometimes the right decision may be to increase the amount. Sometimes it may be to maintain it, and sometimes changing circumstances may justify reducing it.
The mistake is allowing a number chosen years ago to continue indefinitely without asking whether it is still relevant.
10. Treating Every SIP as a Separate Investment Instead of Part of a Plan:
This may be the easiest mistake to overlook because every individual decision can appear reasonable.
Fund A was started for long-term investing. Fund B came from a recommendation. Fund C looked attractive because of performance. Fund D began after a salary increase. Each SIP is running on time, so everything appears organised.
But zoom out and ask: What is the complete portfolio trying to achieve?
You can have five disciplined SIPs and still have an unorganised portfolio.
Instead of judging each monthly debit separately, look at the portfolio together. Identify which goal each investment supports, whether funds overlap, whether the contribution is meaningful for that goal, and whether the overall risk makes sense for the timelines involved.
That is the difference between having SIPs and having SIPs that have a clear role.
Frequently Asked Questions:
Common SIP mistakes include starting without a defined goal, selecting mutual funds mainly from recent returns, choosing an arbitrary contribution amount, accumulating too many similar funds, stopping because markets fall, expecting guaranteed returns and never reviewing the investment.
A broader mistake connects many of these together: assuming that because the SIP debit happens automatically, the investment itself no longer requires thought.
Not automatically. Multiple SIPs can serve different purposes when the underlying mutual funds have clear and relevant roles.
The problem begins when new funds are repeatedly added without checking existing categories, underlying exposure, possible overlap and the goals already being funded. Diversification should be assessed at the portfolio level rather than by simply counting SIPs.
A market fall alone should not automatically determine the decision. Consider the original goal, remaining investment horizon, financial circumstances, risk profile and whether anything fundamental has changed.
Also remember that stopping an SIP only stops future instalments. It does not automatically sell the mutual fund units you already own.
There is no universal SIP amount for beginners. The amount needs to remain affordable, but it can also be evaluated against the goal, possible future requirement, money already accumulated and time remaining.
A smaller SIP can be a perfectly reasonable starting point. What matters is understanding what the amount may realistically contribute towards and reviewing it as circumstances change.
There is no single review frequency appropriate for every investor. A periodic review is useful, and an additional review may become relevant after meaningful changes in income, family responsibilities, goals, investment horizon or financial circumstances.
The purpose of reviewing is not frequent switching. It is checking whether the fund, contribution and original purpose still fit together.
Disclaimer
This article is intended solely for general investor education and information. It should not be treated as personalised investment, tax, legal or financial advice, detailed financial planning, or as a recommendation to buy, sell, switch, continue or hold any particular mutual fund scheme or investment product.
Individual mutual fund decisions depend on factors including the investor’s stated financial goals, risk profile, investment horizon, liquidity requirements, existing investments and financial circumstances. Examples, calculations and calculator outputs are illustrative and based on assumptions; actual mutual fund returns are market-linked and may differ materially.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor, ARN 353817, and may receive commissions from Asset Management Companies on investments made under Regular Plans.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.
This version is deliberately different from our earlier mutual-fund articles. We have not added another Hexo acronym or framework just for differentiation. The unique idea is built naturally through all ten mistakes: automation can make an investment easy to continue, but it can also hide mistakes for years if the purpose, amount, fund or timeline was never properly understood.