
Returning to India from the USA? What Happens to Your 401(k), RSUs, Mutual Funds and NRE/NRO Accounts?
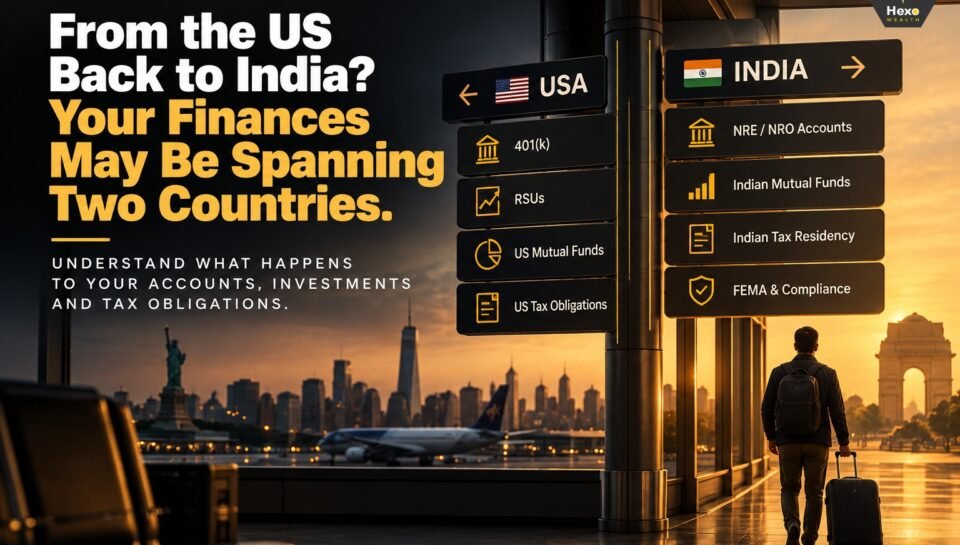
Moving back to India after several years in the US can make your financial life look divided between two countries.
You may have a 401(k) with an old employer, RSUs sitting in a US brokerage account, Indian mutual funds linked to an NRE account, an NRO account receiving income in India and perhaps US investments that you intend to keep. The natural instinct is to ask what should be closed, transferred or sold before the move.
But returning to India from USA does not create one financial switch on the day you land.
Your bank-account status, Indian tax residency, US tax obligations and taxation of individual assets can all change at different times.
That distinction should come before any investment decision.
First Understand the Four Clocks That Change When You Return
Consider someone who moves from California to India permanently on 1 December.
Their NRE account may need attention because their FEMA status has changed. Their Indian income-tax status for that tax year still depends on statutory residency tests. Their US tax status may continue if they remain a US citizen or green-card holder, while an RSU scheduled to vest in February creates another separate tax event.
One move can therefore create four different timelines.
Clock | What It Determines |
FEMA status | Which Indian bank/investment accounts you may hold |
Indian tax status | NR, RNOR or ROR and scope of Indian taxation |
US tax status | Whether US worldwide-income/reporting obligations continue |
Asset event | Tax/compliance consequences of vesting, sale, withdrawal or redemption |
This is the first mistake to avoid: using one residency label for every financial decision.
1. What Happens to Your 401(k) After Returning to India?
Returning home does not automatically require you to withdraw your 401(k).
After leaving a US employer, the available options can generally include leaving eligible money in the former employer’s plan, rolling it into another eligible retirement arrangement such as a traditional IRA, or taking a distribution, subject to the particular plan’s rules. A qualifying rollover can defer US taxation, while a taxable withdrawal may create income tax and, if taken before age 59½, an additional 10% US tax may apply unless an exception is available.
So 401(k) for Returning NRIs should not begin with: “Should I withdraw everything before leaving America?”
Start instead with three separate decisions:
Option | What to Examine |
Keep the 401(k) | Plan access, fees, investment choices and future distribution rules |
Rollover | Whether a direct rollover is permitted and its US tax treatment |
Withdraw | US tax, possible additional early-distribution tax and Indian tax consequences |
A rollover and a withdrawal are not the same transaction.
The important 2026 India tax change
For tax year 2026-27 onwards, India’s new Income-tax framework provides relief for eligible income accruing inside qualifying foreign retirement-benefit accounts through Section 158, Rule 74 and Form 40. The United States is one of the notified countries.
Where the statutory conditions are satisfied, eligible account income can be taxed in India in the year in which that income is taxed upon withdrawal or redemption in the notified country, rather than automatically creating an accrual-year mismatch.
This matters because US retirement arrangements often defer tax until money is withdrawn.
However, do not assume every US retirement account is identical. A traditional 401(k), Roth 401(k), traditional IRA and Roth IRA can have different US tax characteristics, while the Indian relief itself requires the account to meet the definition of a qualifying retirement-benefit account.
So the useful first step is to document the account rather than liquidate it.
Keep:
- Original plan statements
- Contribution history where available
- Account type
- Employer information
- Rollovers already completed
- Withdrawal eligibility
- Year-end values
- US tax records
Those records become far harder to recreate ten years later.
2. RSU Taxation in India: Separate the Grant, Vesting and Sale
RSUs create a different problem because one grant can span your employment in both countries.
Suppose a US employer grants RSUs while you are working in Seattle. You move to India eighteen months later, but half the grant remains unvested.
It would be too simplistic to conclude either: “The RSUs were granted in America, so India has nothing to do with them.” or: “They vested after I moved to India, so the entire award is automatically Indian income.”
For Indian tax purposes, employer-provided securities can create a salary/perquisite event when the specified securities are allotted or transferred, while a later disposal can create a separate capital-gains event.
For a cross-border employee, the employment period connected with the award can make sourcing and treaty analysis more complicated because employment remuneration is linked to where the relevant employment is exercised.
That makes RSU Taxation in India a documentation problem as much as a tax-rate problem.
Before moving, preserve a grant-wise record containing:
- Grant date
- Vesting schedule
- Number of shares
- Vesting/allotment dates
- Fair market value used by payroll
- US tax withheld
- W-2/payroll records
- Sale dates and proceeds
- Brokerage statements
- Periods during which employment services were performed in each country
Do not rely only on your brokerage’s current portfolio value. For a returning employee, vested shares, unvested RSUs and shares already sold are three different buckets.
3. NRE and NRO Accounts After Returning to India
This is one of the most misunderstood parts of the move.
Some returnees assume that if they qualify as RNOR for Indian income tax, they can continue operating NRE and NRO accounts exactly as before.
That mixes two different laws. FEMA determines whether you can hold NRE/NRO accounts. Income-tax residency determines how your income is taxed.
Under RBI rules, when a person returns to India for employment, business or another purpose indicating an intention to stay for an uncertain period, an NRE account should be redesignated as a resident account or eligible funds can be transferred to an RFC account. NRO accounts may similarly be redesignated as resident rupee accounts.
So NRE and NRO Accounts After Returning to India should be handled broadly like this:
Existing Account | After a Permanent Return |
NRE savings account | Redesignate as resident account or consider eligible RFC treatment |
NRO account | Redesignate as resident rupee account |
FCNR(B) deposit | May generally continue until original maturity, subject to applicable rules |
Resident Foreign Currency account | Can be relevant for eligible returning residents wanting to retain foreign currency |
Existing FCNR(B) deposits of returning Indians may continue until maturity at the contracted rate, with conversion options thereafter.
The important takeaway is simple: Do not wait for your Indian tax status to become ROR before informing your bank that you have permanently returned.
The FEMA clock may have moved much earlier.
4. Your Indian Tax Status May Move Through NR, RNOR and ROR
Your Indian income-tax residency does not simply change because your flight landed.
It is tested separately for each tax year using the statutory day-count and history rules. Someone who has lived abroad for several years may qualify as Resident but Not Ordinarily Resident (RNOR) after becoming resident, but RNOR is not a fixed “two-year exemption” automatically granted to every returning NRI.
For RNOR status, prior years of non-residence and days spent in India over the preceding years matter.
Why does this matter?
Because the scope of Indian taxation changes materially.
Broadly:
- Non-resident: foreign income is generally outside Indian taxation unless it has the required Indian nexus.
- RNOR: many items of foreign income can remain outside Indian taxation, subject to the nature, source and receipt of the income.
- ROR: worldwide income generally enters the Indian tax net, subject to treaty relief and specific provisions.
This means your 401(k), foreign dividends, US brokerage account and RSUs should not be analysed only by asking whether they are located outside India.
Your tax status for that particular year matters.
5. Your US Tax Status May Continue Even After You Move
This is the second residency trap.
An Indian professional on an H-1B visa who leaves the US and no longer meets US tax-residency rules may have a very different future US tax position from someone who returns to India while remaining a US citizen or green-card holder.
US citizens and US resident aliens are generally subject to US tax on worldwide income even while living abroad. Green-card holders generally continue to have US filing obligations until their status ends under the applicable rules, subject to treaty positions in appropriate cases.
So before deciding what to invest in after returning, answer: Will I remain a US person for tax purposes?
That one answer can materially change how Indian investments need to be evaluated.
6. What Happens to Mutual Fund Investments for Returning NRIs?
There are actually two separate questions hidden inside this keyword.
Indian mutual funds you already own
Returning to India does not itself mean every Indian mutual fund must be redeemed.
But your investor records should reflect your new status. Changes in KYC information need to be updated, and bank mandates should also reflect the accounts you are now legally operating.
So review:
- Residential status in KYC
- Indian address
- Bank mandate
- NRE/NRO linkage
- FATCA/CRS information
- Nomination
- Whether the fund still serves the original goal
Do not redeem a long-term investment merely because the bank account linked to it needs redesignation.
Those are two different decisions.
US mutual funds and ETFs
If you continue holding US investments after moving to India, their Indian tax treatment changes as your Indian residency evolves. Once global income becomes taxable in India, foreign dividends and gains may enter Indian reporting and taxation, subject to applicable treaty provisions and foreign-tax-credit rules.
But there is an equally important reverse issue.
If you remain a US person, check before buying Indian mutual funds
A US citizen or other US tax person investing in non-US pooled investment vehicles may encounter the US Passive Foreign Investment Company (PFIC) regime. Form 8621 reporting can apply to US persons who directly or indirectly hold interests in PFICs.
Many returning professionals miss this because they think: “I live in India now, so I should simply start investing like any other Indian resident.”
That may be fine from the Indian side, but it may create a separate US tax/reporting issue if US tax-person status continues.
This is one reason Mutual Fund Investments for Returning NRIs should be reviewed from both countries’ perspectives before fresh investments are started.
7. Foreign Asset Reporting Becomes Important as Your Status Changes
Foreign assets do not disappear from the compliance picture merely because you stop sending money overseas.
A returning professional may still hold:
- 401(k)
- US brokerage account
- Vested employer shares
- US bank account
- Foreign mutual funds or ETFs
- Other overseas financial interests
When you become an Indian resident and ordinarily resident, Indian foreign-asset and foreign-income reporting can become relevant. The Indian tax-return guidance specifically distinguishes RNOR/non-residents from ordinarily resident taxpayers for foreign-asset schedules.
So before the first Indian tax filing after your return, prepare a foreign asset inventory.
Do not wait until the ITR utility asks for information you have not collected.
8. A Return-to-India Sequence That Avoids Mixing the Decisions
The cleanest approach is to organise the move by event rather than trying to solve everything on one weekend.
Before Leaving the USA
Download retirement-plan, brokerage, RSU, payroll and tax records. Confirm 401(k) options and beneficiary information, and understand whether you will remain a US tax resident or US person after relocating.
Soon After Returning
Inform Indian banks of the residency change and begin redesignating NRE/NRO accounts where required. Update investment KYC and bank mandates rather than allowing records to continue showing an outdated non-resident status.
Before Your First Indian Tax Filing
Determine your Indian tax status for that specific year. Review the treatment of the 401(k), RSUs, foreign income and foreign assets, including whether the Section 158/Form 40 retirement-account election is relevant.
Before Starting New Investments in India
Check both sides of the border.
Ask whether you remain subject to US worldwide-income/reporting rules, whether an Indian investment creates US reporting complications, and how the investment fits into the financial goals you now expect to fund in India.
This order matters because tax status should influence investment structure, not be discovered after the investment has already been made.
What NRI Investment Planning in India Should Look Like After You Return
The phrase NRI Investment Planning in India is often used broadly, but once you permanently return, the problem changes.
You are no longer simply deciding where an NRI should invest.
You are transitioning:
- US assets → Indian life
- NRI banking → resident banking
- foreign-income treatment → potentially worldwide-income taxation
- employer equity → personal portfolio
- two-country compliance → one coordinated financial record
That is why the first question after returning should not be: “Which investment should I start in India?”
It should be: “Which parts of my financial life have already changed status, which will change later, and what needs to be completed before I invest anything new?”
For eligible investors whose transition includes Indian mutual funds, Hexo Wealth Associates LLP can facilitate and service mutual fund investments within its role as an AMFI-registered Mutual Fund Distributor, based on the investor’s stated goals, investment horizon, risk profile and individual circumstances.
Cross-border tax, FEMA, 401(k), RSU and US tax-status questions should be evaluated separately with appropriately qualified professionals.
Hexo Wealth Associates LLP | AMFI-registered Mutual Fund Distributor | ARN 353817
Conclusion
Returning to India from USA is not simply a relocation of your home.
It is a transition between two financial systems.
Your 401(k) may remain in America. Your RSUs may continue vesting. Your NRE account may need redesignation before your Indian tax status becomes ROR. Your US tax obligations may continue even though you no longer live there. And your Indian mutual-fund decisions may have US consequences if you remain a US tax person.
That is why the return should be managed through four separate clocks:
- FEMA status.
- Indian tax status.
- US tax status.
- Asset-event timing.
Once those four are clear, the individual decisions around the 401(k), RSUs, bank accounts and investments become much easier to organise.
The mistake is not keeping assets in two countries.
The mistake is assuming that every asset changes status on the day you board the flight home.
Disclaimer
This article is intended solely for general investor education and information. It should not be treated as personalised investment, tax, legal, FEMA, retirement-account or financial-planning advice, or as a recommendation to buy, sell, transfer, withdraw, rollover, continue or hold any particular investment or financial product.
US and Indian tax consequences can vary materially based on citizenship, green-card status, tax residency, RNOR/ROR status, employment history, vesting periods, retirement-account structure, source of income, treaty provisions and individual circumstances. Cross-border taxation of 401(k)s, RSUs, foreign securities and foreign-tax credits should be reviewed with appropriately qualified tax professionals in the relevant jurisdictions.
Terms including Returning to India from USA, 401(k) for Returning NRIs, RSU Taxation in India, NRE and NRO Accounts After Returning to India, Mutual Fund Investments for Returning NRIs and NRI Investment Planning in India are used for general educational discussion and should not be interpreted as an offer of tax, legal or SEBI-registered investment-advisory services.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor | ARN 353817 and may receive commissions from Asset Management Companies on investments made under Regular Plans.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.
Frequently Asked Questions:
No. Returning to India does not by itself require a 401(k) withdrawal.
Depending on the plan, possible choices can include keeping eligible money in the former employer’s plan, completing an eligible rollover or taking a distribution. Withdrawal can have materially different US and Indian tax consequences, so the three options should not be treated as equivalent.
It depends on your Indian residential status, the nature of the retirement account and whether the qualifying foreign-retirement-account relief is available.
From tax year 2026-27, Section 158 and Rule 74 provide an option, through Form 40, to align the Indian taxation timing of qualifying retirement-account income with taxation upon withdrawal or redemption in a notified country, subject to the prescribed conditions.
Do not assume so.
RNOR is an income-tax classification, while eligibility to hold an NRE account is governed by FEMA residency. On a permanent return for employment, business or another purpose indicating an intention to stay in India for an uncertain period, the NRE account generally needs to be redesignated or handled through an eligible alternative such as RFC
RSUs can involve an employment-income event when employer shares are allotted/transferred and a separate capital-gains event when the shares are later sold.
For awards spanning US and Indian employment periods, the tax position can become more complex because grant, vesting, service location, residency and foreign taxes may all matter. Keep grant-wise records rather than relying only on the brokerage statement.
Not merely because you returned.
The more immediate operational requirement is generally to update your residential/KYC status and eligible bank mandate. Whether an individual mutual fund should be continued, reviewed or redeemed is a separate investment decision.
The Indian investment may be legally available depending on the fund and investor circumstances, but US tax consequences also need to be checked.
US persons holding certain foreign pooled investments can encounter PFIC rules and Form 8621 reporting. That issue should be understood before making fresh Indian mutual-fund investments.