
How to Choose the Best Fixed Deposit Investment Plan for Your Financial Goals
A fixed deposit looks simple because the interest rate is known when you invest. You choose an amount, select a tenure and receive the principal plus applicable interest according to the deposit terms.
But the highest Fixed Deposit Interest Rate does not automatically make an FD the best choice for your financial goal.
A deposit offering a slightly higher rate may mature too late, carry different repayment risk or become less attractive after tax. Another FD may appear to offer a lower return but give you better access to the money exactly when you need it.
That is why choosing a Fixed Deposit Investment Plan should begin with the job the money needs to perform, not with whichever rate happens to be highest on a comparison page.
1. Identify Your Financial Goals Before Choosing an FD
Before comparing banks or rates, answer one question: When will I actually need this money?
That date determines far more than most investors realise.
Consider three situations.
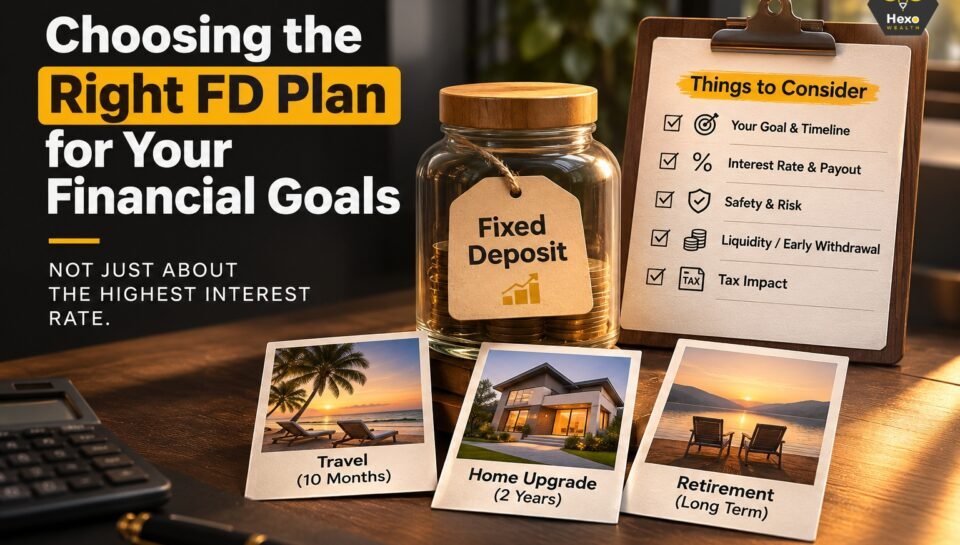
- Family holiday after 10 months: access to the money on time may matter more than locking into a longer FD for a marginally higher rate.
- House renovation after two years: the maturity date can be matched reasonably closely with the expected payment.
- Periodic income after retirement: the payout structure may matter more than the final maturity value.
A common mistake is selecting a three-year FD because its rate appears better even though the money may be required after eighteen months. If the FD then has to be closed early, the applicable premature-withdrawal terms can change the actual interest earned.
So rather than asking: “Which tenure gives the highest rate?”
Ask: “Which maturity date fits the date on which this money gets a job?”
Your FD should mature because you need the money, not merely because an attractive tenure happened to appear on the rate card.
2. Compare Fixed Deposit Interest Rates, Not Just Advertised Returns
Fixed Deposit Interest Rates matter, but a rate should never be compared in isolation.
Two deposits both advertising 7% can produce different experiences depending on the compounding method, payout frequency, premature-withdrawal terms and tax applicable to the investor.
When comparing two FDs, place these details beside the rate:
- Interest rate for the exact tenure you want
- Compounding frequency
- Cumulative or periodic payout
- Expected maturity amount
- Premature-withdrawal treatment
- Tax treatment of interest
- Institution accepting the deposit
There is another reason not to chase today’s highest rate.
Interest-rate cycles change.
In October 2026, the policy repo rate was increased by 25 basis points to 5.50%. By early November, the published range for bank term-deposit rates above one year was broadly around 6.00% to 6.75%. Rates offered by individual institutions and tenures can differ and can change over time.
Once an FD is booked, its contracted rate is generally fixed for that deposit. But when the FD matures, the rate available for reinvestment may be completely different.
So an FD fixes today’s rate for today’s tenure. It does not fix the rate you will receive after maturity.
3. Understand the Different Fixed Deposit Investment Options in India
Not every product carrying the words “fixed deposit” has the same protection.
That distinction matters when comparing Fixed Deposit Investment Options in India.
Bank Fixed Deposits
Bank FDs are offered for specified tenures at stated rates by eligible banks.
Eligible deposits are covered by DICGC insurance up to ₹5 lakh per depositor per bank, including principal and interest, subject to the applicable rules.
An important detail is often missed.
Suppose you have:
- ₹3 lakh FD at Branch A
- ₹3 lakh FD at Branch B
- ₹2 lakh savings balance
all with the same bank and in the same right and capacity.
For deposit-insurance purposes, these balances are aggregated. Opening several accounts or using several branches of the same bank does not create a separate ₹5 lakh insurance limit for every branch.
Deposits with different insured banks are considered separately for the insurance limit.
Corporate Fixed Deposits
Corporate FDs are deposits accepted by eligible companies under the applicable regulatory framework.
They can offer rates and tenures different from bank deposits, but the repayment ultimately depends on the issuing company.
Corporate FDs are not covered by DICGC deposit insurance.
NBFC Fixed Deposits
Certain NBFCs are authorised to accept public deposits, but not every RBI-registered NBFC can do so.
An investor should verify that the NBFC is specifically permitted to accept public deposits. Current rules also require applicable deposit-taking NBFCs to maintain at least the prescribed investment-grade credit rating.
The important distinction is: “Fixed” describes the deposit terms. It does not mean every issuer carries the same repayment risk.
4. Evaluate the Institution Before Investing
Suppose one institution offers 6.8% while another offers 7.4%. The natural reaction is to compare the extra 0.6%. But the better question is: What additional risk, restriction or condition am I accepting for that additional rate?
Before placing a deposit, examine:
- Regulatory status: Is the institution legally permitted to accept that type of deposit?
- Deposit protection: Does DICGC cover the deposit, and how much of your total balance with that bank falls within the limit?
- Credit rating: Where relevant, what is the latest rating and outlook?
- Repayment capacity: For corporate or NBFC deposits, consider the issuer’s financial position and ability to meet its obligations.
- Terms: Understand maturity, interest calculation, payout frequency and premature withdrawal provisions.
A credit rating is useful information, but it remains an assessment of credit risk rather than a guarantee that repayment can never be delayed or defaulted.
This is particularly important when a higher-yielding FD is being chosen specifically because it pays more than a bank deposit.
5. Select a Deposit Tenure That Matches Your Requirements
The wrong FD tenure can turn a predictable product into a liquidity problem.
Imagine you have ₹8 lakh that may be required for two separate expenses:
- ₹3 lakh after one year
- ₹5 lakh after three years
Putting the entire ₹8 lakh into one three-year deposit could mean breaking part or all of the FD when the first expense arrives.
A more deliberate structure could align the maturity dates with the expected cash requirements.
This is where FD laddering can be useful.
Instead of placing a large amount into one deposit, the money can be divided among deposits maturing at different times.
For example:
|
Amount |
Maturity |
|
₹2 lakh |
1 year |
|
₹2 lakh |
2 years |
|
₹2 lakh |
3 years |
|
₹2 lakh |
4 years |
The objective is not necessarily to generate the highest possible return.
The advantage is that only part of the money is locked until each maturity date. It can also reduce the risk of having the entire amount mature at one point when reinvestment rates happen to be unattractive. Recent FD discussions increasingly highlight laddering for exactly these liquidity and reinvestment considerations.
A useful rule is: Do not select the longest tenure you can tolerate. Select the tenure that fits when the money may actually be required.
6. Understand Cumulative and Non-Cumulative Fixed Deposits
Two investors can choose the same bank, same deposit amount, same tenure and same headline rate but still require different payout structures.
Cumulative Fixed Deposit
Interest is accumulated according to the deposit terms and paid along with the principal at maturity.
This can make sense when the investor does not need the interest during the deposit period and wants the amount to accumulate until the goal date.
Non-Cumulative Fixed Deposit
Interest is paid periodically according to the selected option, which may include monthly, quarterly, half-yearly or annual payouts depending on the institution.
This may be relevant when the objective is periodic cash flow rather than building the largest possible maturity amount.
The distinction matters particularly for retirees.
Someone looking for monthly cash flow and someone setting aside money for a future expense should not necessarily choose the same FD simply because the interest rate looks similar.
Ask:Do I need income from this money before maturity, or do I need the money itself to grow until maturity?
That usually makes the choice much clearer.
7. What Should You Know About Corporate Fixed Deposit Investment?
A Corporate Fixed Deposit Investment often attracts attention because the advertised rate can be higher than that of some bank FDs.
But the difference in rate should be interpreted together with the difference in risk. Unlike eligible bank deposits, corporate FDs are not protected by DICGC. Repayment depends on the company’s ability to honour its obligation.
Before considering one, examine:
- Latest credit rating and outlook
- Issuer’s financial position
- Repayment history
- Deposit tenure
- Interest payout structure
- Premature-withdrawal conditions
- Whether the issuer is legally permitted to accept the deposit
- Whether the additional rate reasonably compensates for the additional risk being accepted
One mistake is particularly worth avoiding: Do not turn an extra interest rate into a substitute for issuer due diligence.
If an institution offers noticeably more than alternatives, the first response should not automatically be excitement.
It should be curiosity about why.
8. Consider Taxation and Premature Withdrawal Conditions
There are two numbers investors often confuse:
- TDS
- Actual tax liability.
They are not the same.
Under the current rules, the threshold for TDS on relevant bank, post-office and qualifying co-operative-bank interest is generally ₹50,000 for non-senior citizens and ₹1 lakh for senior citizens in a tax year.
Crossing the threshold can trigger TDS, but TDS itself does not determine the final amount of tax payable. FD interest generally forms part of taxable income, with the final liability depending on the taxpayer’s applicable circumstances and tax regime.
That means an 7% FD is not necessarily a 7% post-tax return.
What about tax-saving FDs?
Certain qualifying five-year tax-saving deposits can form part of the aggregate deduction available for specified savings instruments, subject to the applicable tax provisions and conditions.
However, the corresponding deduction is not available under the default new concessional tax regime. Under the Income-tax Act, 2025, the broadly equivalent specified-savings deduction is contained in Section 123 read with Schedule XV, with an aggregate limit of ₹1.5 lakh where applicable.
These deposits also come with a lock-in, so the tax feature should not be considered without also considering liquidity.
Premature withdrawal
Before booking a normal FD, check:
- Is premature closure allowed?
- What interest rate will apply if the FD is closed early?
- Is there an additional penalty?
- Is partial withdrawal possible?
- Is a loan or overdraft against the FD available?
- Will breaking the FD disturb the financial goal it was meant to fund?
The best time to understand an FD’s premature-withdrawal rule is before you need the money urgently.
Keeping a separate emergency reserve can reduce the likelihood of having to break a goal-linked FD at the wrong time.
9. How to Choose the Best Fixed Deposit Schemes for Investors
There is no single deposit that qualifies as the Best Fixed Deposit Investment Plan for every investor.
Instead of ranking FDs only by rate, use this outcome-based comparison:
|
Factor |
Question to Ask |
|
Purpose |
What is this money meant for? |
|
Maturity |
Will the FD mature when I need the money? |
|
Interest rate |
What rate applies to this exact tenure? |
|
Institution |
Who is responsible for repayment? |
|
Protection |
Does DICGC apply, and how much is covered? |
|
Credit risk |
What issuer risk am I accepting? |
|
Liquidity |
What happens if I need the money early? |
|
Payout |
Do I need periodic income or accumulation? |
|
Tax |
What could the return look like after tax? |
|
Reinvestment |
What happens when the FD matures? |
This leads to a better definition of “best”.
The best FD is not automatically the one with the highest rate. It is the deposit whose maturity, issuer risk, liquidity, protection and post-tax characteristics fit the job assigned to that money.
A Simple FD Outcome Check
Before confirming any deposit, ask 4 final questions:
- Maturity fit: will this money become available around the date I actually need it?
- Protection fit: how much of my money is covered, and who ultimately owes me repayment?
- Liquidity fit: what happens if the financial goal arrives earlier than expected?
- Post-tax fit: what might I actually retain after applicable tax rather than what the advertisement shows?
If one of those answers is unclear, comparing another 0.25% or 0.50% of interest may be premature.
Explore Fixed Income Options With Greater Clarity
Choosing a fixed deposit is not only an interest-rate decision.
A deposit is ultimately a promise that a particular amount will be available under particular terms at a particular point in time. The usefulness of that promise depends on whether the institution, maturity date, liquidity and tax treatment actually match your requirement.
For investors who also hold mutual funds through Hexo Wealth Associates LLP, fixed deposits and other financial assets can be viewed separately from the mutual fund distribution relationship when understanding the broader purpose and timeline of different investments.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor | ARN 353817. Its AMFI registration relates to mutual fund distribution and should not be interpreted as authorisation to provide investment-advisory services or as regulatory approval to distribute every fixed-income product.
Any FD or bond transaction, where separately available, should be undertaken only through the relevant issuer or appropriately authorised platform/arrangement after reviewing the applicable product documentation.
Frequently Asked Questions:
A fixed deposit involves placing a specified amount with an eligible deposit-taking institution for a selected tenure under agreed interest terms.
Depending on the product, interest may accumulate until maturity or be paid periodically. The appropriate structure depends on when the money is required and whether the investor needs periodic cash flow.
Do not compare only the advertised interest rate.
Look at the exact tenure, maturity date, institution, deposit protection, credit risk, premature-withdrawal terms, payout structure and tax implications. A deposit becomes more suitable when those characteristics match the purpose for which the money is being kept.
Not necessarily.
For DICGC purposes, eligible deposits held with the same bank in the same right and capacity are generally aggregated, including deposits across different branches. The insurance limit is currently ₹5 lakh per depositor per bank, including principal and interest.
Not automatically.
Some corporate FDs may offer higher rates, but they carry issuer-related repayment risk and do not have DICGC protection. The additional interest should therefore be assessed alongside the issuer’s financial position, credit rating, deposit terms and your own ability to accept that risk.
That depends on the specific deposit terms.
Many normal FDs permit premature closure subject to an interest adjustment or penalty, while certain deposits may have stronger restrictions. Check these rules before investing rather than assuming the entire amount will always be immediately accessible without cost.
FD interest is generally taxable according to the investor’s applicable tax rules.
TDS may apply once the prescribed threshold is crossed, but TDS is only tax deducted at source and does not necessarily equal the investor’s final tax liability.
FD laddering means dividing a larger amount across deposits with different maturity dates rather than locking the entire amount into one tenure.
This can provide periodic access to portions of the money and reduce dependence on one reinvestment date. It does not guarantee higher returns, and the selected maturities should still reflect the investor’s actual cash-flow requirements.
Choose the Maturity Before Chasing the Rate
An FD is often described as a simple investment because its interest rate is predetermined.
But the more useful question is not simply: “What rate am I getting?”
It is: “Will this money be available, from the right institution, under acceptable conditions, exactly when I need it?”
A slightly higher rate cannot compensate for every maturity mismatch, liquidity problem, tax impact or issuer risk.
Start with the goal date. Then examine the institution, protection, withdrawal terms and post-tax outcome. Compare the rate after those questions are clear.
Disclaimer
This article is intended solely for general education and information. It should not be treated as personalised investment, tax or legal advice, or as a recommendation to invest in any particular bank deposit, corporate deposit, NBFC deposit, bond or other financial product.
Terms including Fixed Deposit Investment Plan, Fixed Deposit Interest Rates, Fixed Deposit Investment Options in India, Corporate Fixed Deposit Investment and Best Fixed Deposit Investment Plans are used for general educational discussion. The word “best” does not imply an independent ranking, guarantee or universal recommendation.
Interest rates, tax provisions, TDS thresholds, credit ratings, deposit conditions and regulatory requirements can change. Investors should verify the latest applicable terms directly with the relevant institution and review product documentation before making a transaction.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor | ARN 353817. AMFI registration relates to mutual fund distribution and should not be interpreted as SEBI-registered investment-advisory status or as approval for other financial products.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.