
How to Set Financial Goals and Create an Investment Plan to Achieve Them
Most people already have financial goals: a home. Children’s education. A family holiday. Retirement. Perhaps a larger car or the freedom to stop working earlier than expected.
The difficulty usually begins when those goals have to compete for the same monthly income.
A nationwide household survey found that children’s education was the most frequently identified top financial goal, followed by supporting family members, growing wealth and buying a home. Retirement was the number-one goal for only a small proportion of households.
This is why merely saying, “I want to invest for my future,” is not enough.
A useful goal needs four numbers and one lever:
- What could it cost?
- When may you need the money?
- How much is already earmarked?
- How much can you sustainably contribute?
- If the numbers do not work, what can realistically change?
Once those answers become clearer, creating an investment plan becomes much more practical.
Why Is Financial Goal Planning Important?
Saving money and funding a goal are not necessarily the same thing.
You may have ₹10 lakh spread between fixed deposits, SIPs and a savings account. But if the same ₹10 lakh is mentally being counted towards a home purchase, your child’s education and retirement, all three goals cannot ultimately use it in full.
That is where many households unknowingly create a gap.
Other common situations include:
- SIPs are running, but nobody knows which goal they belong to.
- A future expense has never been adjusted for inflation.
- Retirement keeps getting postponed because other goals feel more urgent.
- Investments are withdrawn whenever an unrelated expense appears.
- The goal amount changes, but the monthly contribution does not.
- A higher-return investment is chosen simply because the original calculation shows a shortfall.
The key principle is simple: an investment should not be given a goal after it is purchased. The goal should help define what the investment needs to do.
1. Identify and Prioritise Your Financial Goals
Start by writing down the goals competing for your income.
They may include:
- Building an emergency reserve
- Buying a home
- Child’s higher education
- A major family responsibility
- Buying a vehicle
- Retirement
- Travel
- Starting a business
- Another personal milestone
But do not stop at the goal name. “Buy a house” is still only an intention. A more useful version would be: ₹30 lakh towards a home down payment in six years, with ₹6 lakh already accumulated.
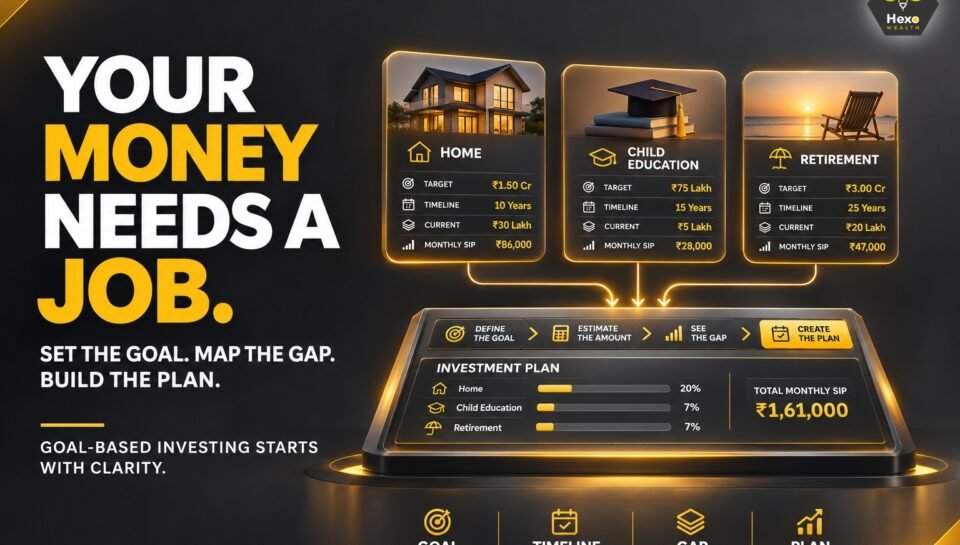
For every important goal, create a simple five-line Goal Card:
Question | Example |
What is the goal? | Home down payment |
What might be required? | ₹30 lakh |
When may it be required? | 6 years |
What is already earmarked? | ₹6 lakh |
What can change if there is a gap? | Deadline, contribution or target |
That final row matters. Some goals are highly flexible. A ₹5 lakh holiday can become a ₹3 lakh holiday or move by one year. Other goals are much less flexible. If university fees are due in July 2034, telling the university that markets have fallen and you would prefer to pay in 2036 may not be realistic.
So prioritisation should not be based only on which goal sounds most important.
Ask:
- How fixed is the amount?
- How fixed is the date?
- What happens if this goal is underfunded?
2. Divide Your Goals Into Short-Term, Medium-Term and Long-Term
Time matters because money required soon cannot be treated exactly like money required decades later.
A simple classification can help.
Short-Term Financial Goals: Up to 3 Years
These may include a holiday, vehicle purchase, course fee or upcoming family expense.
Because the money may be required relatively soon, the ability to access it and limit major fluctuations generally matters more than pursuing maximum growth.
The important question is: can this goal afford a major market fall shortly before the payment date?
If the answer is no, that should influence how the money is organised.
Medium-Term Financial Goals: Around 3 to 7 Years
A home down payment, significant family expense or education requirement several years away may fall here.
These goals need more judgement because there is enough time for some investment growth, but not necessarily enough time to recover comfortably from every market cycle.
Look at:
- How fixed the deadline is
- How much has already been accumulated
- Whether the target can change
- How important liquidity is
- How much fluctuation the household can reasonably accept
Long-Term Financial Goals: More Than 7 Years
Retirement and children’s higher education are common examples, although the actual timeline varies by family.
A longer period can allow different market-linked investment options to be evaluated depending on the investor’s stated risk profile and circumstances.
But there is one mistake worth avoiding: Long-term does not mean permanently long-term.
A goal twenty years away today will eventually become five years away. The investment approach should therefore be reviewed as the deadline gets closer rather than assuming that what suited a fifteen-year horizon will automatically suit the final two years.
3. Calculate How Much You Need to Save and Invest
This is where a financial goal stops being a wish and becomes a mathematical problem. Suppose a higher-education programme costs ₹20 lakh today and the money may be required ten years later.
The eventual requirement may be considerably higher if education costs rise over that period.
For each goal, work through this sequence: Today’s estimated cost → Future requirement → Existing goal-linked money → Potential gap → Time remaining → Contribution to evaluate
Now suppose the calculation indicates that ₹25,000 per month may be required.
But there is an important second calculation. Can the household actually sustain ₹25,000?
If the answer is only ₹15,000, you have discovered something useful. You do not immediately have an investment-selection problem. You have a ₹10,000 monthly funding gap.
That gap may require evaluating one or more levers:
- Can the monthly contribution gradually increase?
- Can bonuses or future lumpsums support the goal?
- Can the goal date move?
- Can the target amount change?
- Will another EMI or commitment end before the goal?
- Does the goal need to be reprioritised relative to other goals?
What should generally not become the automatic solution is simply assuming a higher investment return until the calculator produces the desired answer.
Higher assumed return also usually means accepting a different level of investment uncertainty.
For households managing several future requirements, the Hexo Life Goals Calculator can bring multiple goals into one illustration with separate timelines, future-cost assumptions and existing goal-linked investments. The result is an estimate based on the assumptions entered and not a guarantee of future investment returns.
4. Create a Monthly Investment Plan
Once you know what the goals may require, compare that requirement with what the household can genuinely invest.
Consider someone earning ₹80,000 per month:
Monthly allocation | Illustrative amount |
Household expenses | ₹30,000 |
Rent and loan commitments | ₹15,000 |
Insurance and essentials | ₹5,000 |
Short-term requirements | ₹10,000 |
Long-term investments | ₹15,000 |
Personal expenses | ₹5,000 |
Total | ₹80,000 |
This looks neat on paper. Real life is rarely this neat.There may also be annual insurance premiums, school fees, vehicle repairs, travel, family commitments or medical expenses that do not appear every month.
So do not ask only: “How much is left after this month’s expenses?”
Ask: “How much can I continue investing even in an expensive month?”
That distinction matters because a mathematically perfect ₹30,000 monthly investment that repeatedly gets stopped may be less useful than a sustainable ₹20,000 contribution with a clear mechanism for increasing it later.
A SIP can help automate periodic mutual fund investments, but the SIP itself is not the goal.
The useful sentence is not: “I have three SIPs.”
It is: “I know what each SIP is intended to support and when that money may be required.”
5. Choose Investment Options According to Your Goals
Only after the goal, amount, timeline and contribution capacity are understood should the investment product become the main question.
Different goals can require different investment characteristics.
For money required relatively soon: Liquidity and limiting significant capital fluctuation may deserve greater importance.
For goals several years away: The balance between potential growth, liquidity and market fluctuation becomes more important.
For long-term requirements: Market-linked options, including appropriate mutual fund categories, may be evaluated depending on the investor’s risk profile, investment horizon and individual circumstances.
When considering Mutual Fund Investment Planning in this educational context, examine more than past returns.
Look at:
- Scheme investment objective
- Portfolio characteristics
- Riskometer
- Investment horizon
- Liquidity requirements
- Costs
- Role within the existing portfolio
- Whether another existing investment already serves the same goal
One fund should not be selected merely because it recently appeared at the top of a performance table. And one portfolio does not necessarily need a separate mutual fund for every small financial goal. The goal defines the requirement. The investment should then be evaluated for that job.
6. Review and Adjust Your Investment Plan
A goal does not fail merely because a mutual fund had a weak year. And a goal does not automatically remain on track merely because the portfolio delivered a strong return. A meaningful review should begin with the goal itself. Ask whether any of the four numbers have changed:
Has the target changed?
An overseas education plan may become a domestic one. A ₹30 lakh home down payment may now require ₹40 lakh.
Has the deadline changed?
The home purchase may be delayed, or retirement may be brought forward.
Have existing resources changed?
A bonus, inheritance, redemption or another investment may alter what is already available.
Has contribution capacity changed?
A salary increase may create additional room. A home loan, career break or new dependant may reduce it.
Only after that should you ask whether the existing investment continues to make sense for the revised requirement and remaining horizon.
This creates a useful review rule: Do not change the investment simply because the market changed. Review the investment when the job it needs to perform has changed, or when evidence suggests it is no longer suitable for that job.
A review can therefore result in an increase, decrease, change in investment approach or no change at all.
How Hexo Wealth Supports Goal-Linked Mutual Fund Investments
For investors whose financial goals involve mutual funds, Hexo Wealth Associates LLP supports eligible mutual fund investments within its role as an AMFI-registered Mutual Fund Distributor.
The mutual fund distribution process can include:
- Understanding the investor’s stated financial goals and investment horizon.
- Reviewing existing mutual fund holdings.
- Understanding the investor’s stated risk profile and circumstances.
- Discussing applicable mutual fund scheme information.
- Facilitating eligible SIP and lump-sum investments through Regular Plans.
- Facilitating eligible redemptions, switches and related servicing requirements.
- Periodically discussing whether existing mutual fund holdings continue to remain connected with the stated goal and timeline.
The process does not begin with: “Which fund should you buy?”
A more useful starting point is: “What does this money need to achieve, when may it be required, and what resources are already working towards it?”
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor | ARN 353817 and is not a SEBI-registered Investment Adviser.
Frequently Asked Questions:
In a general educational sense, planning a financial goal means identifying a future requirement, estimating the amount that may be needed, deciding when the money may be required and understanding what resources are already available.
The next step is to identify the potential funding gap and evaluate how it may be funded over the remaining time.
Start with the goal rather than the product.
For each major goal, identify the estimated future requirement, deadline, existing goal-linked resources and amount you can sustainably contribute. Then evaluate investment options based on factors such as the remaining horizon, liquidity requirement, risk and individual circumstances.
Do not automatically solve the shortfall by assuming a higher investment return.
First identify which variables have flexibility. You may need to reconsider the target amount, deadline, monthly contribution, future step-ups, expected lumpsums or relative priority of different goals.
Discovering that a goal is currently underfunded is useful information because it allows the problem to be addressed early.
An SIP is a method of making periodic investments into a mutual fund scheme. It can help automate regular investing, but it does not guarantee that a financial goal will be achieved.
Whether a particular mutual fund and SIP amount are appropriate depends on the goal, investment horizon, investor’s risk profile and other individual circumstances.
Not automatically.
If the required contribution is higher than what you can afford, increasing investment risk does not make the funding gap disappear. First examine whether the contribution, target amount, deadline or other funding sources can change, and then consider investment options appropriate to the revised goal and circumstances.
There is no single review date that suits every household.
A periodic review can be useful, but significant changes in income, responsibilities, target amount, goal deadline or existing resources are particularly important triggers. The purpose is to check whether the goal assumptions and the investment’s role remain relevant, not to change investments unnecessarily.
One investment can form part of an overall portfolio, but mentally allocating the full value of the same money to several separate goals can create a misleading picture.
If ₹10 lakh is expected to fund education, a home purchase and retirement in full, all three calculations may overstate the resources genuinely available to them. Giving important investments a clearly understood role can make goal calculations more realistic.
Start by Giving Every Goal Four Numbers
A financial goal becomes much easier to work with when it stops being described only as “my house”, “my child’s future” or “my retirement”.
Give it four numbers:
the amount, the date, the money already available and the contribution you can sustain.
Then identify the lever you are willing and able to change if the numbers stop working.
That is the difference between simply having financial goals and understanding what it may actually take to work towards them.
For investors whose goal-linked journey includes mutual funds, Hexo Wealth Associates LLP can facilitate eligible mutual fund investments and related servicing within its role as an AMFI-registered Mutual Fund Distributor | ARN 353817.
Disclaimer
This article is intended solely for general investor education and information. It should not be treated as personalised investment, tax, legal or financial advice, detailed financial planning, or as a recommendation to buy, sell, switch, continue or hold any particular mutual fund scheme or financial product.
References to financial goals, goal-based investing, investment plans, short-term goals, medium-term goals, long-term goals and related concepts are used for general educational discussion. Illustrative goal amounts, budgets, calculations and calculator outputs depend on assumptions and should not be interpreted as forecasts or guarantees.
Actual requirements can differ based on inflation, goal timelines, income, liabilities, existing resources, investment performance, risk profile, liquidity needs and individual circumstances.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor | ARN 353817 and may receive commissions from Asset Management Companies on investments made under Regular Plans. It is not a SEBI-registered Investment Adviser.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.