
Retirement Planning in Your 40s: How to Prepare for a Secure Future
Your 40s can feel financially contradictory.
Your income may be substantially better than it was ten years ago, but there may also be a home loan, children’s education, ageing parents, healthcare, lifestyle expenses and other responsibilities competing for the same money. Retirement, meanwhile, has stopped feeling like something that belongs to the distant future.
That is what makes retirement planning in your 40s different.
The challenge is not only to invest more. It is to understand what you have already built, how large the remaining retirement requirement may be, what other goals are competing with it and how your available cash flow could change over the next 10 to 20 years.
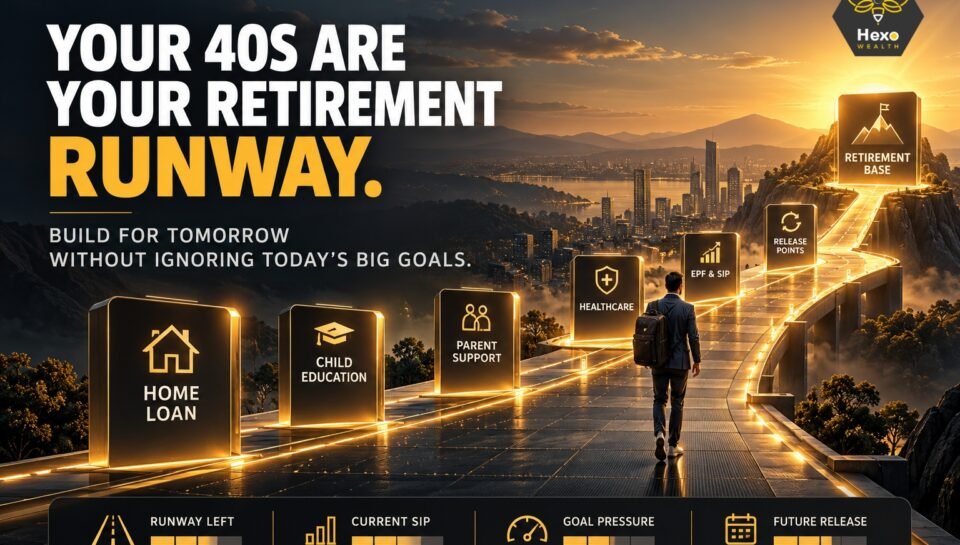
Your 40s are therefore not simply a “catch-up decade”. They are a retirement runway decade.
Why Retirement Planning in Your 40s Matters
If you are 42 and expect to retire at 60, you still have around 18 years before regular employment income may reduce or stop.
That is meaningful time. But every five-year delay now consumes a much larger percentage of the remaining runway than it did when you were 25.
There is another challenge specific to this stage of life. Your 40s may also be when several large financial responsibilities peak together, including:
- Home-loan repayments
- Children’s higher education
- Support for parents
- Lifestyle commitments
- Healthcare and insurance
- Retirement contributions
So the better question is not: “Am I too late?”
It is: “Given what I have today and the years still available, what needs to change from here?”
That is a much more useful retirement question.
1. Start With Your Retirement Lifestyle:
Before estimating a retirement corpus, define what that corpus is expected to support.
Someone who expects to remain in Mumbai or Thane, travel regularly and support family members may have a very different retirement requirement from someone expecting a simpler lifestyle in another city.
Think through:
- Expected retirement age
- Where you may live
- Housing situation
- Current lifestyle you would like to maintain
- Expenses that may disappear
- Expenses that may continue
- Travel and hobbies
- Family responsibilities
- Healthcare requirements
You do not need perfect answers in your 40s. You need assumptions that are realistic enough to produce a useful starting estimate and flexible enough to be updated later.
2. Estimate the Retirement Corpus You May Need:
One of the easiest mistakes is choosing a retirement number because it simply sounds large.
₹1 crore. ₹3 crore. ₹5 crore.
Without connecting that number to future expenses and retirement duration, it tells you very little.
A recent 2026 study covering 1,812 adults aged 30 to 55 found that respondents considered roughly ₹1.5 crore an ideal retirement corpus. Yet the study itself found that this continued to underestimate what retirement may actually require. That is why your own requirement matters more than a popular retirement benchmark.
A retirement estimate can consider: Current monthly expenses → years remaining → inflation → expenses at retirement → expected retirement duration → existing retirement resources
The Hexo Retirement Calculator brings these variables into one illustration. It can compare the estimated retirement requirement with your existing retirement portfolio and ongoing SIPs, then indicate a possible shortfall or surplus under the assumptions entered.
The calculator result is not a retirement prediction. Its real value is helping you stop guessing about the size of the goal.
3. Review What You Have Already Built:
Starting retirement planning at 40 does not necessarily mean starting from zero. By this stage, you may already have:
- EPF
- NPS
- Mutual funds
- Equities
- Cryptos
- SIPs
- PPF
- Fixed deposits
- Other investments
But avoid adding everything together and calling the result “my retirement corpus”.
Suppose you have ₹45 lakh of financial investments, but ₹10 lakh is meant for your child’s education and another amount forms the family’s emergency reserve. The complete ₹45 lakh should not automatically be counted towards retirement.
Before calculating your retirement corpus, place your existing assets into three buckets:
- Retirement-linked: Money you genuinely expect to remain available for retirement.
- Other goal-linked: Money already earmarked for a child’s education, home purchase, emergency reserve or another requirement.
- Flexible / Unassigned: Money that currently has no fixed goal and can be evaluated separately.
That small classification can produce a much more realistic retirement starting point.
The relevant number is not simply: “How much wealth have I accumulated?”
It is: “How much of what I have accumulated is actually expected to remain available for retirement?”
4. Understand Whether Your Current SIP Is Enough:
Many investors start an SIP in their 30s and continue the same amount for years. The discipline is valuable, but the amount may have been chosen when income, lifestyle and retirement expectations were very different. A ₹20,000 retirement SIP started eight years ago does not automatically remain sufficient simply because it is still running.
Review:
- Estimated retirement requirement
- Retirement corpus already built
- Years remaining
- Existing monthly contribution
- Scope for annual increases
- Other major financial commitments
There is also an important behaviour to avoid.
If the retirement gap looks large, the answer should not automatically be: “I need an investment giving much higher returns.”
Current 2026 retirement commentary specifically warns investors who start later against trying to compensate by chasing unrealistic returns, because the resulting investment risk can create another problem instead of solving the original one. A retirement gap can potentially be addressed through several variables, including contribution amounts, future contribution increases, retirement age, expenses and existing resources.
Higher investment risk is not the only lever.
5. Don’t Let Children’s Goals Completely Replace Retirement:
This is one of the most difficult financial conflicts for parents in their 40s.
A child may need higher-education money within five or eight years. Retirement may still be fifteen years away. Naturally, the nearer goal feels more urgent. But there is an important difference between the two.
Education may potentially have several funding routes depending on the circumstances, such as:
- Existing family savings
- Scholarships
- Education loans
- Course or institution choices
- Partial contribution from the child later
Retirement usually has far fewer external funding alternatives.
There is no standard loan designed to fund twenty-five years of post-retirement household expenses. That does not mean retirement should automatically receive every available rupee or that education should be underfunded. It means both should remain visible as separate financial requirements.
For each, define:
What to Compare | Child Education | Retirement |
Estimated requirement | Future education cost | Estimated retirement corpus |
When money is needed | Expected admission/start year | Expected retirement age |
Existing resources | Investments earmarked for education | Investments earmarked for retirement |
Ongoing contribution | Current education-linked savings/investments | Current retirement-linked savings/investments |
Other possible funding sources | Scholarship, education loan, family contribution, where applicable | Pension or other expected retirement income, where applicable |
Potential funding gap | Requirement minus relevant resources | Requirement minus relevant resources |
Looking at both goals separately makes the trade-off clearer. The question is no longer simply whether education or retirement is “more important”. You can see how much each may require, when the money is needed, what is already available and what alternatives may exist if either goal is underfunded.
6. Review Mutual Fund Investments in the Context of Retirement:
A mutual fund may have performed well and still not automatically belong in a retirement portfolio. Likewise, a temporary period of weak performance does not automatically mean it should be replaced. For every important mutual fund linked to retirement, ask:
- Why do I own this fund?
- What role does it perform?
- How many years remain before the money may be required?
- What level of investment risk does it carry?
- Does another fund already perform a similar role?
- Has my risk capacity changed?
- Has retirement moved materially closer?
The last question becomes increasingly important in your 40s.
A fund selected when retirement was twenty-five years away should not remain unquestioned when only eight or ten years remain.
Long term should mean long-term discipline, not permanent neglect.
For a family considering retirement planning in Thane, this review is especially useful when EPF, mutual funds, SIPs, home-loan commitments and children’s goals have accumulated separately over many years and now need to be seen together.
7. Account for Inflation and Healthcare:
Inflation affects more than groceries.
A retirement beginning fifteen or twenty years from now may need to support a much higher cost of living for another twenty-five or thirty years after that.
Healthcare adds another uncertainty.
In a recent 2026 retirement study, 47% of respondents identified rising healthcare costs as a leading retirement concern, while 44% cited age-related health issues. The same study also found that 69% expected some financial support from their family or children after retirement.
Relying on family support should not become the mathematical assumption that makes an otherwise underfunded retirement plan appear workable.
Instead, periodically review:
- General living-cost inflation
- Health-insurance position
- Possible out-of-pocket healthcare expenses
- Healthcare reserve assumptions
- Expected retirement duration
The aim is not to predict medical expenses decades in advance. It is simply to avoid pretending that today’s healthcare costs will remain unchanged forever.
8. Review Your Retirement Plan as Life Changes:
A retirement calculation created at 42 should not remain frozen until 60. Income may rise. Your home loan may finish. Children’s education may eventually be completed. Some expenses may disappear while new responsibilities appear.
This is where the 40s Retirement Runway Check becomes especially useful.
Remaining Runway: how many earning years remain until your expected retirement date?
Retirement Base: how much is genuinely earmarked towards retirement today?
Current Contribution: how much is currently being added towards retirement?
Goal Pressure: which other important goals are competing for the same cash flow?
Cash-Flow Release Points: which large commitments may finish before retirement?
This final question deserves more attention.
Imagine someone aged 44 with:
- ₹40,000 monthly retirement investments
- ₹55,000 home EMI ending at age 51
- ₹20,000 education contribution expected to end around age 52
Looking only at today’s ₹40,000 contribution gives an incomplete picture.
The household can also identify future release points. When major commitments finish, part of that cash flow may potentially be redirected towards retirement, depending on circumstances at the time.
The important step is deciding this deliberately.
Otherwise, an EMI that disappears at 51 can quietly become additional lifestyle spending at 52.
Retirement Planning in Thane: Bringing Your Investments Together
Consider a couple in their mid-40s living in Thane.
They own their home with a remaining loan, have EPF balances, six mutual funds, active SIPs and a child who may enter higher education within six years. Both earn well, yet they are unsure whether they are actually prepared for retirement.
Their first requirement may not be another investment.
It may be one consolidated retirement view:
Retirement Question | What to Identify |
When might retirement begin? | Expected retirement age |
What lifestyle may need funding? | Future expense estimate |
What has already been built? | Retirement-linked investments |
What is being invested now? | Current contributions |
What competes with retirement? | Education, loans, family goals |
What cash flow may free up later? | EMI and goal completion dates |
What potential gap remains? | Requirement vs projected resources |
That is what makes your 40s particularly valuable.
You may no longer have thirty years ahead, but you still have enough time to make deliberate changes before retirement becomes a near-term event.
Frequently Asked Questions:
No. If retirement is expected around age 60, someone in their early 40s may still have close to two decades available.
However, the remaining time should be used more deliberately because competing goals may also peak during this stage. The first step is to understand the retirement requirement, existing retirement-linked resources and potential gap.
There is no universal number or salary multiple that is appropriate for everyone.
A person planning to retire at 55 with high living expenses requires something very different from a person planning to work until 65 with pension income and lower expected retirement expenses.
Your retirement requirement should therefore be linked to your lifestyle, retirement age, existing corpus and expected income sources, not simply your age.
There is no universal SIP amount.
The amount depends on the projected retirement requirement, current retirement corpus, years remaining, existing contribution, income and other financial responsibilities.
If a gap exists, test different contribution and step-up scenarios rather than selecting an SIP amount simply because it sounds affordable.
Mutual funds may form part of retirement investments depending on the investor’s stated goal, investment horizon, risk profile and individual circumstances.
Different mutual fund categories carry different types and levels of risk, and returns are market-linked rather than guaranteed.
They should ideally be treated as two separate requirements rather than allowing one goal to completely replace the other.
Look at the timeline, amount required, resources already available and funding alternatives for each. Retirement generally has fewer external funding options, which is one reason it should not disappear completely from the household’s long-term allocation.
Do not immediately try to solve the gap by assuming higher investment returns.
Review several variables together: current contribution, future Step-Ups, existing assets, possible retirement age, expected expenses and cash flow that may become available after EMIs or other major commitments end.
Start Preparing for Retirement With Greater Clarity
Your 40s are not simply about making up for lost time.
They are about using the remaining runway intelligently.
Understand the lifestyle your retirement may need to support. Estimate the requirement. Separate retirement assets from money meant for other goals. Check whether current contributions remain meaningful. Then identify the financial commitments that may finish before retirement and decide how that future cash flow could be used.
That gives you a much more useful retirement picture than simply asking:
“Am I investing enough today?”
The better question is:
“How can the next fifteen or twenty years of my financial life work progressively harder for retirement?”
For investors whose retirement journey includes mutual funds, Hexo Wealth Associates LLP facilitates eligible mutual fund investments and mutual fund portfolio servicing based on stated goals, investment horizon, risk profile and individual circumstances.
Disclaimer
Hexo Wealth Associates LLP | Hiranandani Estate, Thane AMFI-registered Mutual Fund Distributor | ARN 353817
This article is intended solely for investor education and general information. It should not be treated as personalised investment, retirement, tax, legal or financial-planning advice, or as a recommendation to invest in any particular mutual fund scheme or financial product.
Terms such as retirement planning in your 40s, retirement planning in Thane, retirement corpus, SIP for retirement and similar phrases describe the educational subject discussed in this article. They should not be interpreted as representing Hexo Wealth as a SEBI-registered Investment Adviser or as an offer of detailed financial-planning services.
Calculations, retirement estimates and calculator outputs are mathematical illustrations based on assumptions. Actual inflation, expenses, healthcare requirements, investment returns, retirement age and individual circumstances may differ materially.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor, ARN 353817, and may receive commissions from Asset Management Companies on investments made under Regular Plans.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.