
Short-Term vs Long-Term Financial Goals: How Should You Plan?
A ₹10 lakh requirement three years from now and a ₹10 lakh requirement ten years from now may look similar on paper.
Financially, they are very different problems. The first has limited time to recover if things do not go as expected. The second has a much longer runway, but inflation, changing circumstances and years of future contributions can materially change the amount required.
This is why understanding short-term vs long-term financial goals matters.
But time is only the first part of the decision. Two goals can even have the same deadline and still deserve different treatment because one can be postponed while the other cannot.
A useful way to think about any goal is therefore through three questions:
- When is the money required?
- How flexible is the goal?
- What happens if it is underfunded?
What Are Short-Term and Long-Term Financial Goals?
A financial goal is a future requirement that you expect to fund through income, savings or investments. Goals are commonly grouped according to the amount of time available before the money may be required.
Short-term financial goals:
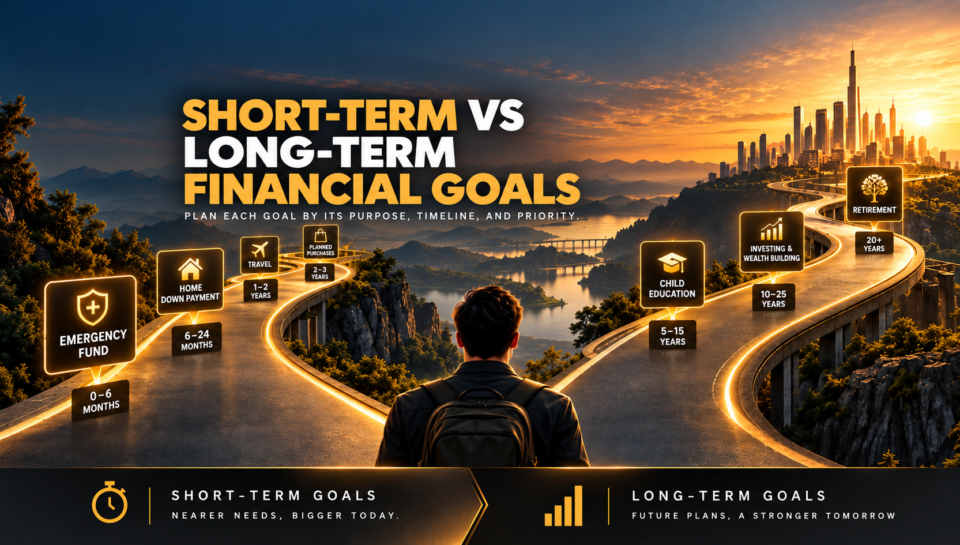
These are requirements expected relatively soon. Examples may include:
- Emergency reserve
- Holiday
- Vehicle purchase
- Professional course
- Near-term home down payment
- Family event
- Planned household expense
Long-term financial goals:
These are generally requirements many years away. Common examples include:
- Retirement
- Child’s future education
- Long-term wealth creation
- Future home purchase
- Building a financial legacy
There can also be medium-term goals sitting between the two. There is no need to become overly rigid about whether a particular goal is exactly “short”, “medium” or “long”. The more useful question is how much time remains and what that time allows you to do.
Why Does the Time Horizon Matter?
Time affects how much uncertainty a goal can reasonably absorb.
Suppose you need ₹10 lakh for a home down payment after three years. A significant decline close to the deadline gives you relatively little time to recover if the purchase cannot be postponed.
Now compare that with retirement twenty years away.
The longer horizon provides more time for contributions to continue and for market-linked investments, where suitable, to experience different market cycles. That does not mean every long-term goal should automatically take high investment risk.
The useful distinction is:
Factor | Shorter-Term Goal | Longer-Term Goal |
Time to recover from fluctuations | Limited | Greater |
Importance of liquidity | Usually higher | Depends on goal |
Inflation impact | Lower period, but still relevant | Often more significant |
Ability to keep contributing | Limited time | More contribution years |
Need for periodic reassessment | Yes | Yes, especially as goal moves closer |
This is why goal based financial planning should begin with the requirement and deadline before the investment product is considered.
Examples of Short-Term Financial Goals
Short-term goals often look easier because the future amount may be easier to estimate. But they can actually create greater pressure because the money is required sooner.
Consider:
- ₹5 lakh for a car after two years
- ₹8 lakh for a professional course next year
- ₹12 lakh for a home down payment after three years
- ₹4 lakh for a planned family event
For each goal, ask four things:
- What amount could be required?
- What is the exact or approximate date?
- What is already available?
- Can the goal be postponed if the money is not ready?
That fourth question is important.
A car upgrade can often wait. A college admission, medical requirement or contractual home payment may not offer the same flexibility. So a short-term goal should not simply become an excuse to chase the highest available return.
Availability of money at the required time matters.
Examples of Long-Term Financial Goals
Long-term goals give you more time, but they also create more uncertainty.
Common examples include:
- Retirement
- Child’s higher education
- A future house
- Financial independence
- Long-term family wealth
- Legacy-related goals
The challenge is that both the goal and your life can change over a long period.
A child who is five today may eventually choose a different course or country. Your expected retirement age may change. The home you imagine buying fifteen years later may cost very differently from today’s estimate.
That is why long-term goals need something short-term goals need less of: regular recalibration.
A longer timeline gives you more time to prepare. It also gives assumptions more time to become wrong.
How Can Inflation Affect a Long-Term Financial Goal?
Inflation matters more visibly when the goal is far away.
Suppose something costs ₹20 lakh today.
- At an assumed 6% annual increase, the same requirement would be roughly ₹47.9 lakh after fifteen years.
- At an assumed 8%, it would be roughly ₹63.4 lakh.
Neither number is a forecast. They simply show how strongly the assumption can influence a long-term estimate.
That is why financial goal planning should work with: Current Cost → Years Remaining → Inflation Assumption → Estimated Future Requirement
A long-term planning number should be treated as a working estimate rather than an exact promise about the future.
What About Medium-Term Financial Goals?
Medium-term goals can be the hardest category because they sit between “money needed soon” and “money needed far in the future”.
Examples may include:
- Home purchase after several years
- Higher studies
- Starting a business
- Career break
- Major family event
- Large planned expense
For these goals, ask:
- How fixed is the deadline?
- How much is already available?
- How much still needs to be accumulated?
- Can the amount be adjusted?
- What level of investment fluctuation can the goal reasonably tolerate?
A seven-year goal that can easily be postponed may allow a different approach from another seven-year goal with a fixed contractual deadline.
Again, timeline alone does not tell the whole story.
How to Plan Your Financial Goals Step by Step
The simplest way to organise several goals is to move from vague intentions to specific requirements.
Step 1: Write Down Every Important Goal:
Put all major requirements on one list rather than keeping them mentally scattered.
For example:
- Emergency reserve
- Car
- House down payment
- Child education
- Retirement
At this stage, do not select investments. First make the goals visible.
Step 2: Add a Timeline:
Give every goal an approximate date.
For example:
Goal | Timeline |
Car | 2 years |
Home down payment | 5 years |
Child education | 12 years |
Retirement | 25 years |
You now have four separate financial requirements instead of one vague portfolio called “my investments”.
Step 3: Estimate the Future Requirement:
Estimate what the goal could cost when it actually arrives. For nearer goals, the estimate may be relatively easier. For longer goals, inflation and changing circumstances deserve more attention.
The objective is not perfect forecasting. It is having a more realistic number than simply using today’s cost.
Step 4: Map Existing Money to Each Goal:
Suppose you already have ₹10 lakh invested. Do not automatically count the same ₹10 lakh towards retirement, education and a future home. Give existing money a clear job wherever possible.
This avoids one of the easiest mistakes in managing multiple goals: counting one asset several times in your head.
Step 5: Identify the Potential Gap:
Now compare what may be required with the resources linked to the goal.
A basic structure is: Estimated Future Requirement − Projected Goal-Linked Resources = Potential Gap or Surplus
The answer will depend on assumptions, particularly for market-linked investments. But it gives you a much clearer decision than simply asking how much you should invest every month.
What If You Have Several Financial Goals at the Same Time?
Most families do. A household may simultaneously be working towards:
- Car in 2 years
- Home in 6 years
- Education in 12 years
- Retirement in 25 years
The mistake is treating the complete portfolio as one pool that will somehow fund everything.
Instead, give every goal its own line: Goal → Timeline → Future Requirement → Existing Resources → Ongoing Contribution → Possible Gap
This is where goal-based investing becomes genuinely useful.
It shows which goals are reasonably funded, which need more attention and which may need a different timeline or amount.
Which Financial Goal Should You Prioritise?
This is where simply labelling goals “short” and “long” becomes insufficient.
Use the Hexo Goal Pressure Check.
For every major goal, ask:
1) Deadline:
How soon is the money required?
A nearer deadline usually creates more immediate funding pressure.
2) Flexibility:
Can the amount or date change?
A vehicle upgrade may be postponed. A school or university payment may offer much less room.
3) Consequence:
What happens if the goal is underfunded?
Some goals create inconvenience. Others may affect education, housing, retirement security or another important family responsibility.
This produces a more useful priority decision than simply saying: “Short-term goal first.” or: “Retirement is always first.”
There is no universal ranking that fits every household.
Two important goals can compete for the same money, and the right answer may involve adjusting timelines, contribution amounts or the goal itself.
Should Short-Term and Long-Term Goals Use the Same Investments?
Not automatically. The investment approach needs to reflect:
- When the money may be required
- How flexible the deadline is
- How important the goal is
- How much fluctuation the investor can tolerate
- What other financial resources exist
Money required soon generally has less time to recover from meaningful market fluctuations.
A longer horizon may permit consideration of different mutual fund categories where appropriate, but a long period by itself does not make every high-risk investment suitable.
There is another useful principle to remember: every long-term goal eventually becomes a short-term goal.
A retirement goal twenty years away will eventually become five years away.
The same is true for education and other dated goals.
As the goal approaches, the investment structure should therefore be reviewed instead of assuming that something chosen fifteen years earlier should remain unchanged forever.
Use a Life Goals Calculator to Put Your Goals in One View
Managing one goal is relatively simple.
Managing four or five goals that all depend on the same household surplus is much harder.
The Hexo Life Goals Calculator brings multiple goals into one view so that different timelines, current costs, existing goal-linked investments and ongoing contributions can be compared together.
That makes it easier to see:
- What each goal may require
- How much is already linked to it
- What current contributions may build towards
- Where a possible shortfall may remain
- Which goals are competing most strongly for the available money
The result remains a mathematical illustration based on the assumptions entered. Its real value is not predicting the future. It is helping you compare competing goals on the same page instead of evaluating them one at a time.
Review Your Goals as Life Changes
Goals are not permanent instructions. Income may increase. A home may be purchased sooner. A child’s education plans may change. Retirement could move forward or backward. So review each goal periodically for:
- Amount
- Deadline
- Existing resources
- Ongoing contribution
- Importance
- Flexibility
And remember one important transition. A goal that started as long term may eventually need to be treated as near term. That is why the question should gradually change from: “How can I build this money?” to: “How important is it that this money is available when the deadline arrives?”
Give Every Goal Its Own Timeline and Purpose
The biggest difference between short-term and long-term financial goals is time, but time should not be viewed in isolation.
A practical goal has three dimensions:
- When is it due?
- How flexible is it?
- What happens if it is not fully funded?
Once those answers are clear, priorities become easier to understand.
Your short-term money does not need to behave like retirement money. Your retirement money does not need to solve next year’s expenses. And the same pool of savings should not be expected to fund several different goals in full.
For investors whose goals involve mutual funds, Hexo Wealth can facilitate eligible mutual fund investments within its role as an AMFI-registered Mutual Fund Distributor, based on the investor’s stated goals, investment horizon, risk profile and individual circumstances.
Hexo Wealth Associates LLP | Hiranandani Estate, Thane | AMFI-registered Mutual Fund Distributor | ARN 353817
Frequently Asked Questions:
The main difference is how much time remains before the money is required. Short-term goals are relatively near, while long-term goals may be many years away.
However, deadline flexibility and the consequence of underfunding also matter. Two goals with the same timeline can still deserve different priorities.
After that, consider emergency liquidity and define future goals before deciding how much can sustainably be directed towards savings or investments.
Examples may include building an emergency reserve, purchasing a vehicle, funding a planned holiday, making a near-term home down payment or preparing for a family expense expected within the next few years.
The important feature is that the money may be required relatively soon, leaving less time to respond if assumptions change.
Retirement, a young child’s future higher education, long-term wealth creation, a future home or another large requirement several years away can be long-term goals.
Because more time is involved, inflation and changing circumstances become particularly important when estimating the requirement.
List every important goal separately and add a timeline, estimated future requirement, existing goal-linked resources and current contribution.
Then compare the potential gaps rather than assuming one combined investment portfolio will automatically fund every goal.
There is no universal order suitable for every household.
Consider how soon the goal arrives, whether the amount or deadline can change and what happens if it remains underfunded. Those three factors usually provide a better basis for prioritisation than timeline alone.
A goal is usually easier to evaluate once you know its approximate future requirement, timeline, resources already allocated towards it and potential gap.
Goal-based financial planning connects money with specific future requirements rather than allowing all savings and investments to remain in one undefined pool.
It helps clarify the amount, timeline, resources already available and possible gap for each goal before investment decisions are considered.
Disclaimer
This article is intended solely for investor education and general information. It should not be treated as personalised investment, financial, tax or legal advice, or as a recommendation to invest in any particular mutual fund scheme or financial product.
References to financial planning, financial goal planning, goal based financial planning and related expressions describe the general financial concepts discussed in this article. Hexo Wealth is not a SEBI-registered Investment Adviser and does not provide detailed financial planning as an investment-advisory service.
Mutual fund suitability depends on factors including the investor’s stated goals, investment horizon, risk profile, liquidity requirements, existing investments and individual circumstances. Examples, inflation calculations and calculator outputs are mathematical illustrations based on assumptions and do not assure investment returns or achievement of any financial goal.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor, ARN 353817, and may receive commissions from Asset Management Companies on investments made under Regular Plans.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.