
How to Create a Personal Financial Plan From Your Monthly Salary
Your salary gets credited. EMIs and bills go out. SIPs may get deducted automatically. Groceries, school expenses and weekend spending happen through the month, and before long, the next salary arrives. The system appears to be working because everything is getting paid. But that does not necessarily tell you whether your monthly income is also preparing for the expenses and goals that have not arrived yet.
So instead of beginning with a rule such as “invest 20% of your salary”, begin by understanding the different jobs the same salary has to perform.
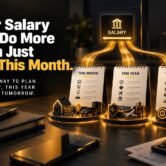
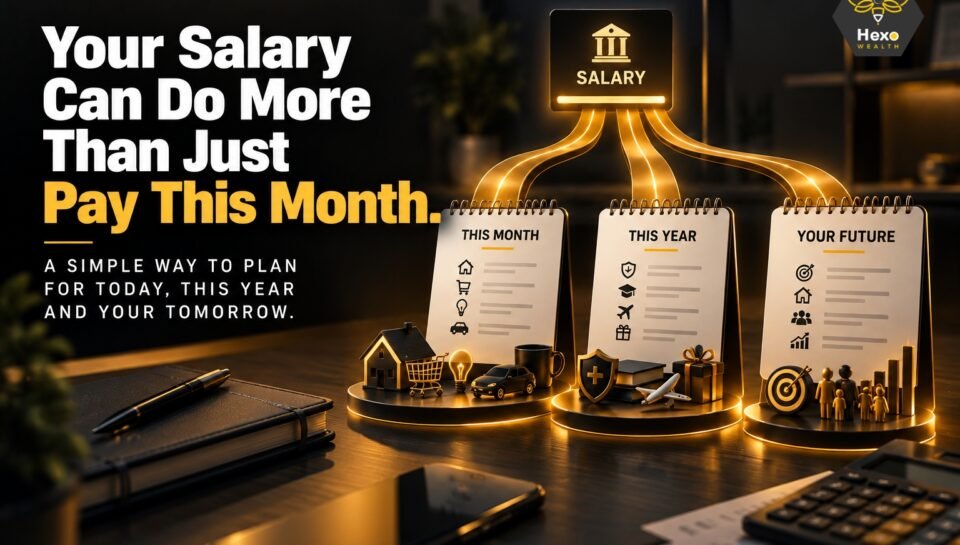
A useful way to see it is through 3 calendars:
- This month: regular household expenses and commitments
- This year: predictable expenses that do not occur monthly
- Your future: financial goals that may be several years away
A salary plan becomes much clearer when all three calendars are visible.
What Is Personal Financial Planning?
In simple terms, personal financial planning is the process of organising income, expenses, liabilities, savings and investments around present requirements and future goals.
For a salaried professional, that process can begin with five questions:
- What actually reaches my bank account every month?
- What does my household need to run normally?
- What commitments are coming later in the year?
- Which future goals am I trying to fund?
- What amount can I realistically set aside without repeatedly having to reverse the decision?
That final question matters.
An investment amount is useful only if the household can reasonably sustain it. So instead of forcing your salary into a ready-made formula, build the formula around the life the salary actually needs to support.
Step 1: Start With Your Actual Take-Home Salary
Your CTC is useful when discussing compensation.
Your bank credit is more useful when organising your month. If your CTC is ₹18 lakh but ₹1.15 lakh actually reaches your bank each month, the monthly structure needs to work with ₹1.15 lakh.
Begin by listing the commitments already competing for that amount:
- Rent or home-loan EMI
- Groceries and household costs
- Utilities
- Commuting
- Loan repayments
- School or childcare costs
- Insurance
- Family responsibilities
- Lifestyle spending
- Existing savings or investments
At this stage, do not worry about whether the amounts are “good” or “bad”.
The first objective of personal finance management is visibility. You cannot organise a number you have not first understood.
Step 2: Don’t Forget Expenses That Don’t Arrive Monthly
This is where a monthly budget can give a false sense of surplus.
Suppose your take-home salary is ₹1,00,000 and your normal monthly spending is ₹65,000. It appears that ₹35,000 remains.
Now add:
- Annual insurance premiums: ₹48,000
- Vehicle servicing and repairs: ₹24,000
- School-related annual payments: ₹48,000
- Family travel and celebrations: ₹60,000
That is ₹1.80 lakh over the year, or an average of another ₹15,000 per month.
Your apparent ₹35,000 surplus is therefore closer to ₹20,000 before considering other priorities.
This is the second calendar.
A simple calculation is: Take-home salary − regular monthly expenses − monthly provision for predictable annual expenses − existing commitments = working monthly surplus
Calling this a working surplus rather than immediately calling it “money available to invest” is useful because the emergency reserve and financial goals still need to be considered.
Step 3: Separate Needs, Wants and Future Money
Once your first two calendars are visible, organise the salary into broad roles.
A) Needs:
These keep the household functioning and meet unavoidable commitments. They may include rent, EMIs, food, essential transport, necessary insurance and school expenses.
B) Wants:
These improve lifestyle but generally offer greater flexibility. Dining out, shopping, entertainment, premium subscriptions and discretionary travel may fall here.
C) Future Money:
This supports financial resilience and future requirements. It could include building an emergency reserve and putting money aside for goals expected over different timelines.
Rules such as 50:30:20 can provide a useful reference, and they remain prominent in current salary-budgeting content. But even current discussions acknowledge that fixed percentages can become unrealistic when housing costs, income levels and household responsibilities differ.
Someone supporting parents and paying a home loan cannot reasonably be expected to have the same split as someone earning the same salary with no dependants or liabilities.
The percentage should describe your situation. It should not override it.
Step 4: Build a Financial Cushion Before Stretching Your Investments
Your future-money bucket has another job before aggressive long-term investing. It needs to help the household absorb disruption.
Consider what would happen if:
- Salary stopped temporarily
- A major repair became necessary
- A family emergency required money
- An unavoidable expense arrived unexpectedly
An accessible reserve can reduce the need to redeem long-term investments whenever short-term life becomes uncomfortable.
There is no universal emergency-fund number suitable for every household. Even current Indian emergency-fund discussions commonly differentiate requirements based on dependants, EMIs, job stability and whether the household relies on one or multiple incomes.
Ask instead:
- What are our unavoidable monthly costs?
- How large are our EMIs?
- How many people depend on this income?
- Is there another earning member?
- How stable is the income?
- What insurance and accessible savings already exist?
The purpose is not to maximise the reserve. It is to prevent Calendar 1 emergencies from repeatedly stealing money from Calendar 3 goals.
Step 5: Turn Future Wishes Into Financial Goals
Now move to the third calendar.
“Buy a house someday” is a wish. “Build ₹25 lakh towards a home down payment in six years” is a financial goal you can begin evaluating.
The same applies to:
- Child education
- Retirement
- A major family responsibility
- A future home
- Another important long-term requirement
For every major goal, answer:
Question | Example |
What is the goal? | Child’s higher education |
What might it cost today? | ₹20 lakh |
When could the money be required? | 10 years |
What is already earmarked? | ₹5 lakh |
What might the requirement become? | Depends on assumptions |
What gap may remain? | To be estimated |
The Hexo Life Goals Calculator can bring several such goals into one view, with separate timelines, current costs and investments already linked to each goal.
The calculator result should remain an illustration, not a prediction. Its real value is helping a household stop treating retirement, education and home purchase as one vague bucket called “future savings.”
Step 6: Prioritise Your Goals
The goals list can easily become larger than the available salary surplus.
You may simultaneously want to:
- Strengthen the emergency reserve
- Repay debt
- Buy a home
- Fund education
- Prepare for retirement
- Increase investments
Trying to maximise everything immediately can create a plan that looks impressive on paper but becomes impossible to sustain after three months.
Instead, classify requirements by both urgency and flexibility.
A) Needs attention now:
These may include essential reserves, unavoidable liabilities and goals with near deadlines.
B) Needs consistent progress:
Longer-term goals such as retirement may not be urgent today, but completely postponing them can create a much harder requirement later.
c) Can potentially wait:
Some goals may have adjustable amounts or timelines.
This is an important part of goal-based financial planning. Prioritising does not mean abandoning a goal. It means deciding which rupee needs to work where first.
Step 7: Decide How Much of Your Salary Can Actually Be Invested
This is where the usual question finally becomes useful: “How much should I invest every month?”
There is no universal percentage. The number depends on:
- Take-home salary
- Regular expenses
- Annual commitments
- Liabilities
- Emergency reserves
- Dependants
- Existing resources
- Financial goals
- Time remaining
The cleaner sequence is: Goal → Future Requirement → Existing Resources → Potential Gap → Time Available → Monthly Contribution to Evaluate
Suppose your total goal calculations suggest investing ₹50,000 every month, but the Three-Calendar Salary Check shows only ₹25,000 of sustainable monthly capacity.
That is useful information.
It tells you the solution cannot simply be: “Somehow invest ₹50,000.”
You may need to reconsider goal timelines, amounts, priorities, future salary increases or other variables. A realistic plan is better than a mathematically perfect plan that the household cannot actually follow.
Step 8: Connect Your SIP to a Goal
A SIP is a method of making periodic investments into a mutual fund.
It should not become a financial goal by itself.
Instead of saying: “I have a ₹15,000 SIP.” try being able to say: “This ₹15,000 SIP is one part of what I am building towards this particular long-term goal.”
For SIP investment planning in an educational sense, periodically ask:
- What requirement is this SIP supporting?
- How far away is that requirement?
- What has already accumulated?
- Can I continue the contribution comfortably?
- Has my income changed?
- Has the goal amount or deadline changed?
Mutual fund returns are market-linked and are not assured or guaranteed, so a SIP amount should not be treated as proof that a goal will necessarily be achieved.
The recurring debit creates discipline. The connection to the goal creates purpose.
Step 9: Use Salary Hikes to Review the Plan
A pay increase gives you more money. It does not automatically tell you what to do with it.
Suppose take-home salary increases by ₹15,000 per month. Before converting the entire increase into lifestyle spending or automatically increasing every SIP by the same percentage, check all three calendars again.
Ask:
- Have regular household costs changed?
- Have annual commitments increased?
- Does the emergency reserve need attention?
- Has a new goal appeared?
- Is an existing important goal falling behind?
- Can one existing contribution simply be increased?
Current personal-finance content often recommends using salary hikes to increase savings rates, which can be useful. But the amount should still reflect the household’s updated numbers rather than an automatic formula.
A salary hike is therefore best viewed as a reallocation opportunity. Decide where the new money needs to work before lifestyle quietly absorbs all of it.
Step 10: Review Your Financial Plan as Your Life Changes
A salary system created at age 28 should not remain untouched at age 38 simply because the standing instructions still work.
Revisit the structure after events such as:
- Job change
- Salary increase
- Marriage
- Childbirth
- Home purchase
- New loan
- Major debt repayment
- New dependant
- Significant bonus
- An important goal moving closer
The review should return to the same basic question: Do my three calendars still fit inside the income I have today?
If the answer changes, the allocations may need to change too.
That is normal.
A useful financial structure should evolve with the household rather than forcing the household to continue following outdated numbers.
A Simple Monthly Salary Planning Framework
The entire process can be condensed into the Three-Calendar Salary Check.
Calendar 1: This Month
Fund the household’s current operating needs.
Check: regular expenses, EMIs and recurring commitments.
Calendar 2: This Year
Pre-fund expenses you already know are coming, even though they are not monthly.
Check: premiums, school costs, repairs, subscriptions, travel and other planned irregular expenses.
Calendar 3: Your Future
Direct sustainable surplus towards resilience and defined goals.
Check: emergency reserve, nearer goals and longer-term requirements.
Then review the flow in this order: Income → Monthly Life → Annual Commitments → Resilience → Goals → Investments → Review
The purpose is not to make salary management complicated. It is to stop treating every rupee left in the bank at month-end as genuine surplus.
Your Salary Is Monthly. Your Financial Plan Should Look Beyond This Month.
A monthly salary creates a regular rhythm.
But your money is simultaneously funding today’s household, expenses arriving later this year and goals that may still be ten or twenty years away. That is why creating a personal financial plan from your monthly salary, in an educational sense, should not begin with one universal savings percentage.
Begin instead by seeing all three calendars.
- Understand what arrives.
- Understand what is already committed.
- Provide for the expenses that are easy to forget.
- Build financial resilience.
Then connect what genuinely remains with the goals that matter.
For investors whose goal-linked journey includes mutual funds, Hexo Wealth, within its role as an AMFI-registered Mutual Fund Distributor, can facilitate eligible mutual fund investments based on the investor’s stated goals, investment horizon, risk profile and individual circumstances.
Hexo Wealth Associates LLP | Hiranandani Estate, Thane | AMFI-registered Mutual Fund Distributor | ARN 353817
Frequently Asked Questions:
Start with the amount actually credited to your account, not only your CTC. Map regular monthly expenses and then convert predictable annual expenses into monthly provisions so you can understand what genuinely remains.
After that, consider emergency liquidity and define future goals before deciding how much can sustainably be directed towards savings or investments.
There is no universal percentage suitable for every household. Although percentage-based rules can provide a reference, the sustainable amount depends on income, regular and annual expenses, liabilities, dependants, emergency reserves, existing resources and future goals.
A lower sustainable percentage that can increase over time may be more useful than a higher target that repeatedly needs to be stopped.
One practical way is to think across three calendars rather than only one budget: current monthly expenses, predictable annual commitments and future requirements.
Once these are visible, you can understand how much genuinely remains for financial resilience and longer-term goals.
Regular investing can support discipline, but the amount and mutual fund investment should first be considered in the context of your cash flow, emergency requirements, stated goal, investment horizon and risk profile.
A SIP is an investment method. It does not by itself determine whether the rest of your financial structure is adequate.
Used educationally, goal-based financial planning means connecting money with clearly defined future requirements rather than investing without knowing what the money is expected to achieve.
A goal is usually easier to evaluate once you know its approximate future requirement, timeline, resources already allocated towards it and potential gap.
Revisit the complete salary structure before automatically increasing spending or investments. Check whether current expenses, annual commitments, emergency reserves or important goals have changed.
Then decide how much of the higher income should be directed towards existing goals, additional investing or other priorities.
Disclaimer
This article is intended solely for investor education and general information. It should not be treated as personalised investment, financial, tax or legal advice, detailed financial planning, or as a recommendation to invest in any particular mutual fund scheme or financial product.
The phrases personal financial planning, financial planning, financial planning for salaried professionals, goal-based financial planning, personal finance management and similar terms are used solely in an educational context. They should not be interpreted as representing Hexo Wealth as a SEBI-registered Investment Adviser or as an offer by Hexo Wealth to provide detailed financial-planning services.
AMFI’s guidance distinguishes the role of an MFD from detailed financial planning and holistic investment advice, which are regulated separately. AMFI
Mutual fund suitability depends on factors including the investor’s stated goals, risk profile, investment horizon, liquidity requirements and individual circumstances. Any examples, future-value calculations or calculator outputs are mathematical illustrations based on assumptions and do not assure investment returns or achievement of any financial goal.
Hexo Wealth Associates LLP is an AMFI-registered Mutual Fund Distributor, ARN 353817, and may receive commissions from Asset Management Companies on investments made under Regular Plans.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.